The Hidden Trap of Borrowing Money: Why Unsecured Loans Feel Out of Reach
Let’s be completely honest—getting a loan without putting your house or car on the line feels almost impossible right now. You walk into a bank, ask for an unsecured personal loan, and suddenly the loan officer treats you like a huge risk. I used to think banks just hated lending out money, but here is the truth I found out: banks actually want to give you cash. You just need to know how their hidden approval checklist works. Today, I am going to show you exactly how to bypass the automated rejections and make your profile look incredibly safe to any lender.
Imagine having an urgent money problem but zero assets to pledge as security. You need cash for an emergency or a major life event right now. Your heart races every time you look at your empty savings account.
The stress builds up in your chest, making it hard to sleep at night. You want a loan, but you do not want to risk your home or car. This is why unsecured bank loans seem like the only option, but getting one feels like climbing a giant wall.
Why do so many people fail to get the loan they need? The main reason is the flood of bad advice.
- Fake online lenders promise instant cash with zero credit checks just to steal your personal data.
- Confusing bank jargon hides the real costs of the loan in tiny text that nobody reads.
- Bad advice from friends often tells you to apply everywhere at once, which destroys your credit score.
- Unrealistic expectations make people believe banks give out money without checking their income or job status.
This constant struggle does not just hurt your wallet. It also hurts your mind and your confidence.
When a bank rejects your loan application, they rarely tell you the real reason. They just send a cold, automated letter that says you do not meet their standards. This leaves you feeling lost and confused.
You might start to believe that banks only lend money to people who are already rich. This thought makes you angry and ready to give up.
But you must remember that banks are not your enemies. They are just businesses that want to avoid taking bad risks. They have a checklist, and they use it to grade every single person who applies.
If you do not know what is on that checklist, you are basically flying blind. Once you learn the secrets of how banks think, the entire process changes.
You stop guessing and start preparing your application like a pro. You can build a profile that banks will find hard to reject. It takes some time and effort, but the financial peace of mind is worth it.

What You Will Learn Today (Quick Takeaways)
- Check for tiny errors: A single mistake on your credit report can ruin your chances. Dispute them instantly.
- Keep your debt bucket light: Make sure your fixed monthly bills take up less than 36% of your total income.
- Go local: Skip the giant national banks. Community banks and credit unions listen to your real story instead of just looking at a computer screen.
- Time it right: Applying at the end of a business quarter (March, June, September, December) often gives you a better chance of approval.
The Insider Blueprint: How to Prepare Your Profile for Fast Approval
Before you read the exact steps below, check out this quick video to discover the number one hidden secret banks use to approve loans. Once you finish watching, keep reading the rest of the guide to build a financial profile they simply cannot reject!
Step 1: Fix Your Financial Report Card (The Credit Score)
Your credit score is the very first thing a bank looks at. Think of it as your adult report card.
If you have bad grades, the teacher will not recommend you for a scholarship. In the same way, a bad credit score tells the bank you might not pay them back.
Most people think their credit score is a permanent mark. They believe that once it is low, it stays low forever.
But this is a huge mistake. Here is a quick pro tip from my own mistakes: I used to ignore my credit report because I was simply too scared to look at the bad numbers. Once I finally checked it, I found a tiny error from an old phone bill that was dragging my score down for no reason. Getting that single mistake removed boosted my numbers in just a few weeks and completely changed how banks saw me.You can change your score faster than you think.
- Myth: Checking your own credit report drops your score.
- Fact: Checking your own score is a "soft pull" and does absolutely nothing to your points. You can check it every day if you want to!
- Myth: You need to carry a little bit of debt to show you are responsible.
- Fact: You do not need to pay interest to build credit. Paying your credit card balance to zero every single month is actually the best thing you can do for your score.
Start by getting a free copy of your credit report. Look at every single line carefully.
You might find mistakes from years ago that should not be there anymore. Sometimes, a bank forgets to update your payment status.
If you find an error, write to the credit bureau immediately to fix it. This simple step can jumpstart your score in just a few weeks.
Also, make sure you pay your bills on time every single month. Set up automatic payments so you never miss a due date.
Even one late payment can drop your score by fifty points. That small mistake could cost you thousands of dollars in high interest rates.
Keep your credit card usage low as well. Try to use less than thirty percent of your total limit.
If your limit is ten thousand dollars, do not owe more than three thousand. This shows the bank that you have self-control.
Step 2: Master Your Debt-to-Income Ratio (The Bucket Principle)
Banks do not just care about your credit score. They also want to know if you can actually afford a new monthly payment.
To do this, they look at your Debt-to-Income ratio. This is often called the DTI ratio.
Let us use a simple analogy to understand this concept. Imagine your monthly income is a bucket of clean water.
Your rent, car payments, and credit card bills are holes in the bottom of that bucket. The water that leaks out represents your fixed monthly costs.
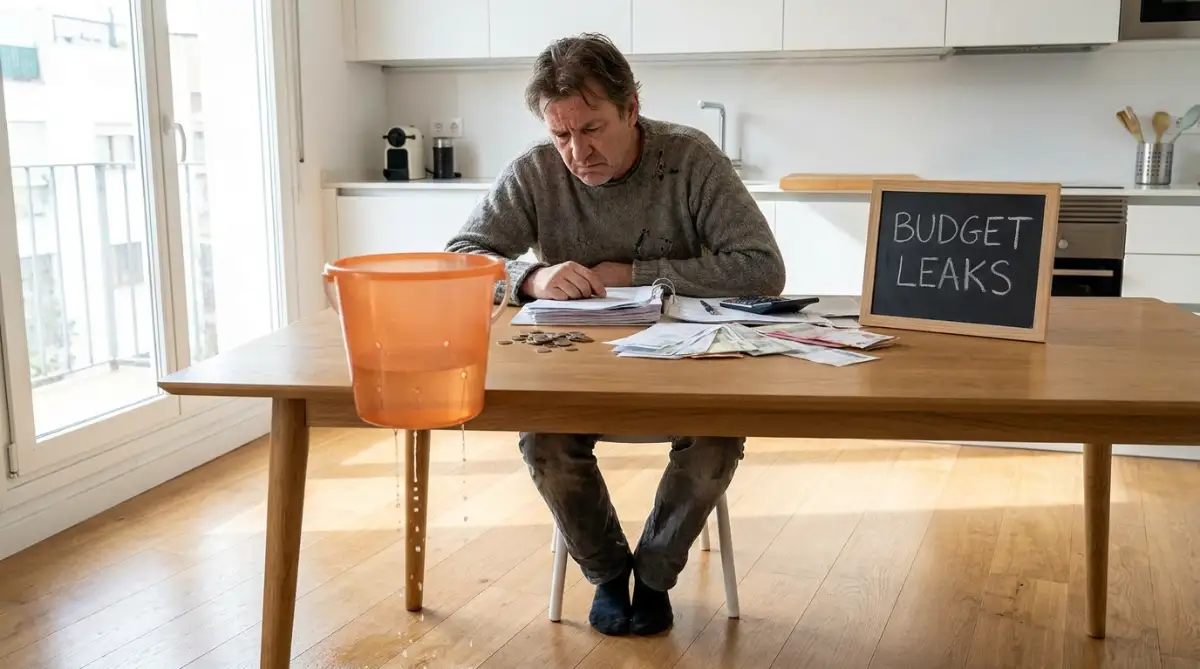
If your bucket has too many holes, most of the water leaks out. The bank will see that you have very little water left to live on.
They will worry that adding a loan payment will empty your bucket completely.
To calculate your DTI, add up all your monthly debt payments. Then, divide that number by your total monthly income before taxes.
For example, let us say you make five thousand dollars a month. If your debts cost you two thousand dollars, your DTI is forty percent.
Most banks prefer a DTI ratio that is under thirty-six percent. If your ratio is higher than forty-five percent, getting an unsecured loan is very hard.
Quick Question: What if my income changes every month?
How do I prove my income for the DTI ratio if I am a freelancer or gig worker?
If you drive for Uber, freelance, or run a small shop, banks will not look at just one month. Instead, they will usually ask for your tax returns from the last two years. They take your total yearly income from those taxes and divide it by twelve to find your monthly average. My advice? Always deposit your cash earnings straight into your bank account so there is a clear paper trail for the loan officer to see.
But you can fix this ratio with a few smart moves. Try to pay off your smallest credit cards first to eliminate those monthly payments.
Even paying off a small hundred-dollar debt can lower your ratio. This small change makes you look much safer to the loan officer.
You can also try to add extra income to your profile. If you have a side job, make sure you report it on your tax forms so banks can see it.
Step 3: Find the Right Financial Partner (Not All Banks Are Equal)
Many borrowers make the mistake of applying to the biggest bank in town. They think big banks have the most money, so they must be the easiest to deal with.
But the opposite is often true. Large national banks have very strict automated systems.
If your profile does not fit their perfect mold, a computer will reject you in seconds. No human will ever look at your story or your situation.
Instead, you should look at smaller local options. Community banks and credit unions are often much better for unsecured loans.
These smaller institutions care about their local community. They are more likely to listen to your personal story.
If you have been a member of a local credit union for years, they already know you. They can see your direct deposits and your savings habits.
This personal relationship can help you get approved even if your credit score is not perfect.
Let us look at a real scenario. Think about a borrower named Mark who needed ten thousand dollars for home repairs.
He went to a giant national bank first. They rejected him because his credit score was sixty points below their limit.
Mark did not give up. He walked into his local community bank where his family had accounts for years.
He sat down with a human loan officer and explained his situation. The officer looked at Mark's steady job and approved the loan.
This shows why choosing the right partner is so important. Do not waste your time begging a giant computer to trust you.
Go where people actually know your face and respect your hard work.
Advanced Bank Secrets: How to Make Yourself Irresistible to Lenders
You have already learned how your credit score and your debt ratio affect your loan application. Now, we are going to look at the hidden rules that banks never share with the public. These simple adjustments will help you get approved even faster.
Step 4: The Power of Relationship Banking (The Regular Customer Effect)
Think about your favorite local coffee shop. If you go there every morning, the staff eventually learns your name and your exact order. They might even give you a free cookie once in a while because they value your business.
Banks work in a very similar way. They prefer to lend money to people they already know and trust.
If you want a loan from a specific bank, do not just walk in as a total stranger. Try to open a basic checking account with them at least three to six months before you apply.
Make sure you set up your main direct deposit to land in this new account. This gives the bank a clear, daily view of your real income and cash flow.
They do not have to guess if you can pay them back. They can look at your transaction history and see that you are a responsible customer.
This simple strategy can sometimes bypass strict credit score checks. It turns you from a random risk into a valued local partner.
Step 5: Master the Bank Calendar (The Quota Secret)
Most people think they can apply for a loan at any time of the year. They assume the process is exactly the same on a Tuesday in January as it is on a Friday in December.
But this is not how banking businesses actually operate. Loan officers and bank managers work on strict quarterly sales targets.
They have specific quotas they must meet to get their bonuses. This means their willingness to approve loans changes depending on the calendar.
Generally, banks are much more eager to approve unsecured loans at the end of a business quarter. These periods are usually March, June, September, and December.
During these months, loan officers are often desperate to hit their final numbers. They might overlook minor issues in your profile just to get another loan on the books.
Conversely, try to avoid applying at the very beginning of the year when new targets are still being set.
Let us look at a real-life scenario. Think of a small business owner named Robert who needed fifteen thousand dollars.
He applied in early January and got rejected because the bank was being very careful with its new budget.
He waited, cleaned up his profile, and applied again in late June. Because the bank was trying to meet its mid-year targets, his application went through without any trouble.
Keeping Your Financial Profile Sharp for the Future
Getting one loan approved is a great victory. But you must also think about your long-term financial health.
A good financial profile is like a clean car. If you do not wash it and check the oil, it will eventually stop running.
To maintain a great credit profile, you must build good financial habits. Keep checking your credit report at least twice a year to watch for new errors.
Never close your oldest credit cards, even if you do not use them anymore. The length of credit history accounts for a large portion of your overall credit score.
Closing an old card makes your credit history look shorter, which can lower your score. Keep those old accounts open and put a tiny purchase on them once a year.
Also, try to build an emergency fund that can cover three to six months of expenses.
Having cash in reserve means you will not have to rely on high-interest credit cards when something goes wrong. It keeps your overall debt levels low and your financial peace high.