The Suffocating Weight of Empty Pockets
Let's talk about that mini heart attack you get when you open your banking app. I used to dodge my account balance like it was a scary movie, hoping my money problems would just magically fix themselves. But honestly, running away from the numbers only made my anxiety worse. If you are tired of stretching your last ten dollars until payday, I am going to show you the exact, no-nonsense steps I took to finally stop stressing and take my paycheck back.
This kind of money stress does not just stay in your wallet; it creeps into every single corner of your life. When you are constantly worried about rent or groceries, your brain stays in a continuous state of high alert. You start losing sleep, snapping at your loved ones, and feeling a deep sense of guilt every time you buy something for yourself. Financial anxiety is a quiet thief that steals your peace of mind and your physical health.
Living in this constant state of panic makes it completely impossible to plan for a better future. When you are entirely focused on surviving until Friday, you simply cannot think about building long-term wealth or security. Your mind is too exhausted from fighting the daily fires to start planting seeds for tomorrow. You end up making impulsive, short-term decisions just to find a tiny bit of immediate relief.
But I am here to tell you that this heavy, exhausted version of you does not have to be permanent. You can absolutely break out of this stressful loop and take your power back from your bank account. It takes time and honest effort, but stepping out of the shadows of money fear is entirely possible for anyone.
My Quick Blueprint for Financial Peace (Read This First!)
-
Stop hiding from the math: Write down every single debt and bill today. Seeing the raw numbers removes the fear of the unknown.
-
Plug your money leaks: Use a highlighter on your bank statements to catch sneaky subscriptions and useless impulse buys.
-
Use the 50/30/20 rule: Give your money a clear job so you do not have to rely on guesswork.
-
Automate your future: Move a set amount of cash to your savings the exact day you get paid, before you can spend it.
 Shifting from Panic to Practical Money Management
Before we can start building a healthy financial future, we have to deeply understand what is holding us back. Most of us were never taught how to manage a paycheck, let alone how to grow our savings. We are expected to just magically figure out taxes, credit scores, and investments entirely on our own. This lack of basic education is exactly why money feels so terrifying to the average person.
You cannot fix a problem if you refuse to look closely at what is actually broken. Taking back control means you have to be willing to sit down and face the uncomfortable math. It is entirely normal to feel a wave of nausea when you first start adding up your debts and expenses. However, that temporary discomfort is the only way to find permanent relief from your daily money worries.
Myth vs. Reality in Personal Finance
Let us clear up some common misunderstandings before we map out our action plan.
Myth: You need a massive income to start building meaningful wealth.
Reality: Wealth is built by consistently managing what you already have, regardless of how small the amount is. Small, intentional habits always beat a large, mismanaged paycheck over time.
Myth: Budgeting is a restriction that stops you from enjoying your life.
Reality: A proper budget simply gives your money specific directions instead of wondering where it all went. It actually grants you the freedom to spend on things you love without feeling guilty.
The "Brain Dump" Method for Finding Clarity
Your very first actionable step is getting all those swirling numbers out of your head and onto a piece of paper. Grab a blank notebook and write down every single debt, monthly bill, and minimum payment you can think of. Do not try to organize them perfectly yet; just focus on getting the raw information out in the open. Seeing the actual numbers written down is often much less scary than the imaginary monster in your head.
I used to think tracking every single penny would make me feel far more stressed out and restricted. But my biggest mistake was running away from the numbers, which only allowed my fears to grow larger in the dark. Once I finally sat down and looked at my actual debt, I realized the math was bad, but it was absolutely fixable.
Once everything is written down, you can start grouping these items into clear categories. Separate your absolute necessities like housing and food from your optional expenses like streaming services and takeout dinners. This visual map will immediately show you exactly where your hard-earned dollars are leaking away every month. You will finally have a clear picture of your baseline survival number.
Securing the Leaks Before Building the Ship
Imagine trying to fill up a bucket with water while there are five massive holes in the bottom. No matter how much water you pour in, you will never be able to fill it up completely. Your bank account works in the exact same way when you have hidden subscriptions and impulsive spending habits. You must patch those leaks before you can even think about building serious wealth.
Start by reviewing your last three months of bank statements with a bright highlighter in your hand. Mark every single purchase that was not absolutely necessary for your survival or your work. You will likely be shocked by how much money disappears into random coffee runs, unused gym memberships, and online impulse buys. This is not about feeling bad about your choices; it is about gathering honest data.
Watching someone else break down their money journey can completely change how you view your own bank account. If you are a visual learner, this simple breakdown will show you exactly how to map out your money without feeling overwhelmed.
Once you identify these leaks, you can start making intentional choices about where to cut back. You do not have to cancel everything that brings you joy, but you do need to prioritize. Keep the subscriptions that truly add value to your life and ruthlessly cut the ones you barely use. Redirect all of that saved money directly toward your most pressing financial goals.
Creating a Realistic Action Plan (That Actually Works)
Now that you know where your money is going, you need a system to control where it goes next. Traditional budgeting often fails because people try to be completely perfect and strict from day one. They cut out all fun expenses entirely, get miserable after two weeks, and eventually give up completely. A successful financial plan needs to have room for your actual human behavior.
Instead of a restrictive diet for your wallet, think of your plan as a clear set of guardrails. You want a system that protects your essential needs while slowly building your future security. One of the most effective and simplest frameworks to start with is the 50/30/20 method. It breaks your income down into completely manageable chunks that are easy to track.
Understanding Your Money Buckets
This simple breakdown prevents you from overcomplicating the entire process. If your basic needs are taking up more than fifty percent of your income, you have a clear starting point. You either need to figure out how to reduce your housing costs or focus on increasing your monthly earnings. The goal is to slowly adjust your life until your numbers naturally fit into these comfortable buckets.
Protecting Yourself With an Emergency Buffer
One of the biggest reasons people stay stuck in financial anxiety is the total lack of a safety net. When you have absolutely zero savings, every minor inconvenience turns into a massive, panic-inducing emergency. A flat tire or a broken refrigerator can completely ruin your entire month and force you deeper into credit card debt. Building a starter emergency fund is your absolute best defense against the unpredictability of life.
You do not need thousands of dollars to start feeling a sense of safety and relief. Your first major goal should simply be to save one thousand dollars as quickly as humanly possible. Sell old items around your house, take on a temporary side job, or cut your grocery bill down aggressively for a few weeks. That small pile of cash will act as a shock absorber between you and your daily money stress.
Once you have that initial buffer, you can finally breathe a little easier when unexpected bills pop up. You will no longer have to rely on high-interest credit cards just to survive a bad week. This small step completely shifts your mindset from survival mode into an empowered, planning mode. You are no longer just reacting to life; you are actively preparing for it.
Tackling The Heavy Chains of Debt
Debt is the heaviest anchor pulling down your potential to build true, lasting wealth. It is incredibly hard to invest in your future when your past mistakes are constantly demanding monthly payments. However, attacking your debt randomly without a clear strategy will leave you feeling exhausted and entirely unmotivated. You need a specific game plan to start knocking out those balances one by one.
There are two main strategies for paying down debt, and both are highly effective depending on your personality. The Debt Snowball method asks you to pay off your smallest balances first, completely ignoring the interest rates. This method gives you quick psychological wins, which builds massive momentum and keeps you excited about the process. Seeing an entire credit card balance drop to zero is incredibly motivating and addictive.
The second strategy is the Debt Avalanche, which mathematically saves you the most money over time. With this method, you attack the debt with the highest interest rate first, regardless of the total balance size. This requires more patience because it might take months to see a single account completely disappear. You must choose the method that you know you will actually stick with on your hardest days.
Quick Look: Which Debt Strategy Fits You?
Protecting Your Mental Health During the Process
It is incredibly easy to become completely obsessed with your numbers once you start this journey. You might find yourself checking your bank app multiple times a day or feeling intense guilt over a small treat. Please remember that improving your finances is a long marathon, not a quick weekend sprint. You have to allow yourself some grace when you inevitably make a small mistake along the way.
Reward yourself when you hit important milestones, like paying off a credit card or hitting your first savings goal. These rewards do not have to cost money; it could be a relaxing movie night or a long walk in the park. Celebrating your small wins teaches your brain that managing money can actually be a positive and rewarding experience.
If you fall off track for a week, simply acknowledge what happened and gently redirect your focus. Do not use a single bad spending day as an excuse to completely abandon your entire financial plan. Tomorrow is always a fresh opportunity to make smarter choices for your future self. Building true wealth requires persistence, continuous learning, and a whole lot of self-compassion.
Next-Level Strategies for Lasting Financial Peace
You do not have to pick individual winning stocks to be successful at growing your net worth. The wealthiest people in the world often rely on incredibly boring, repetitive strategies that simply work over long periods. Your main goal right now is to shift your mindset from merely surviving the month to actively building a fortress around your future.
Once your basic emergency fund is fully funded, you can start looking at more advanced ways to protect your hard-earned cash. One of the smartest moves you can make is separating your money into different functional buckets. You should have one account for your daily bills, a completely separate high-yield savings account for emergencies, and an investment account for your retirement. Keeping your spending money far away from your savings completely removes the temptation to make impulsive purchases.
The Psychology of Paying Yourself First
Most people pay their landlord, their internet provider, and their credit card company before they even think about themselves. By the time they finally look at their own savings goals, there is absolutely nothing left in the bank. You have to flip this exact script if you want to permanently escape money anxiety.
Treat your personal savings target like it is the most important monthly bill you owe. When your paycheck arrives, move a set percentage directly into your investments before you buy a single cup of coffee. This simple behavioral shift forces you to live comfortably on the remaining balance. If you want to dive deeper into protecting what you build, learning about securing your personal assets is a great next step.
Turning Active Income into Passive Growth
Your day job is an excellent tool for generating active income, but your physical energy has a strict limit. You can only work so many hours in a week before you completely burn out. This is exactly why you need to convert your active dollars into passive income streams that work while you sleep.
Think of every dollar you save as a tiny worker whose only job is to go out and recruit more dollars. When you put your money into broad market index funds, you own a tiny piece of thousands of successful companies. As those companies grow and make a profit, your wealth naturally grows right alongside them. If you want a safe place to learn the basics, reading secure guidelines for beginner investing directly from official sources will give you immense clarity.
Real-Life Scenario: The Magic of Consistency
Let us imagine a person named David who decides to save just fifty dollars every single week. At first, this feels like an incredibly small amount that will never change his life. He might even feel discouraged when he compares his small progress to the flashy lifestyles he sees on social media. However, David stays completely consistent and refuses to touch that money for any reason.
Over time, that small weekly contribution turns into a massive snowball of compounding wealth. Because he automated the process, he never had to rely on his daily willpower to make the right choice. Decades later, David has built enough wealth to consider buying your very first home without the usual heavy stress. Consistency will always beat massive, random bursts of effort when it comes to personal finance.

The Hidden Traps That Keep Smart People Broke
Even people with massive salaries can find themselves completely paralyzed by money anxiety. It is rarely about how much money you actually make, but rather how you behave when the money arrives. If you do not recognize the common emotional traps, you will continuously self-sabotage your own progress. Awareness is your strongest weapon against repeating the exact same financial mistakes year after year.
We often trick ourselves into thinking that our bad money habits are just temporary phases. We promise ourselves that we will finally start saving next month, but that magical month never seems to arrive. Let us explore the most dangerous pitfalls you must actively avoid on your journey to wealth.
The Silent Danger of Lifestyle Creep
Have you ever noticed that a goldfish will grow to perfectly fit the size of its glass bowl? Human spending habits act in the exact same way when we start earning a little more money. The moment we get a raise at work, we suddenly convince ourselves that we desperately need a nicer car or a bigger apartment. This phenomenon is known as lifestyle creep, and it is the absolute quickest way to stay broke forever.
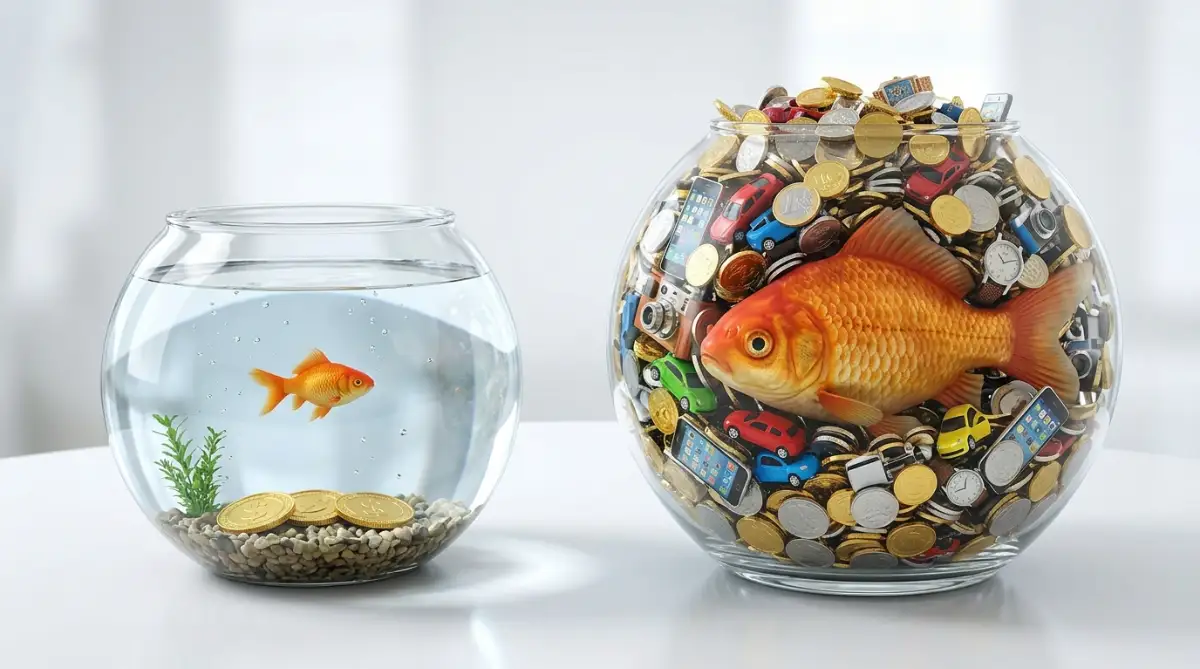
My Quick Reality Check: Are you falling for lifestyle creep?
-
You got a raise this year, but your savings account looks exactly the same.
-
You suddenly feel like your perfectly good phone is "too slow" just because a new one came out.
-
You treat yourself to fancy dinners to celebrate working hard, but stress over the bill later.