The Silent Thief Stealing Our Future Peace
You know that awful sinking feeling when you check your bank balance and wonder where all your money actually went? For a long time, I just ignored my savings, thinking I had decades to figure it out later. But when I finally did the math on what I was losing by waiting, it literally made my jaw drop. Let me show you the exact numbers I found, and how you can fix your savings plan today without eating ramen noodles for the rest of the year.
Saving for my later days felt like an impossible puzzle that I could simply figure out tomorrow. But when I finally sat down and ran the actual numbers, the harsh reality hit me like a ton of bricks. I had not just lost a few months of saving; I had permanently lost out on massive compound growth.
My simple, seemingly harmless choice to wait just a little while longer was now demanding a huge chunk of my current paycheck just to catch up. Everyday people face this exact same invisible burden, silently carrying the weight of financial insecurity on their shoulders.
You start second-guessing every small purchase, feeling guilty about buying a simple cup of coffee. We end up sacrificing our mental peace today because we are absolutely terrified of what might happen tomorrow.
Before You Read On, Here Is The Quick Summary:
- Time is your best friend: Starting your savings today beats waiting for a higher salary later.
- Automate everything: Move your money out of your main account before you have the chance to spend it.
- Kill the leaks: Finding and canceling forgotten subscriptions can easily fund your new savings habit.
- Keep it simple: You do not need Wall Street knowledge to grow your money; you just need consistency.
The Hidden Math That Changes Everything
We often trick ourselves into believing that waiting a few months or even a few years will not make a big difference. We tell ourselves that we will start putting money away as soon as we get that next promotion.
However, money has a very specific rule when it comes to time, and it is entirely unforgiving. The secret ingredient to building wealth is not about having a massive salary from day one. It is all about giving your money enough time to multiply on its own without you doing extra work.
When you push your saving schedule back by just a short period, you are not just missing out on the exact dollars you did not deposit. You are missing out on the money those dollars would have earned for you automatically.
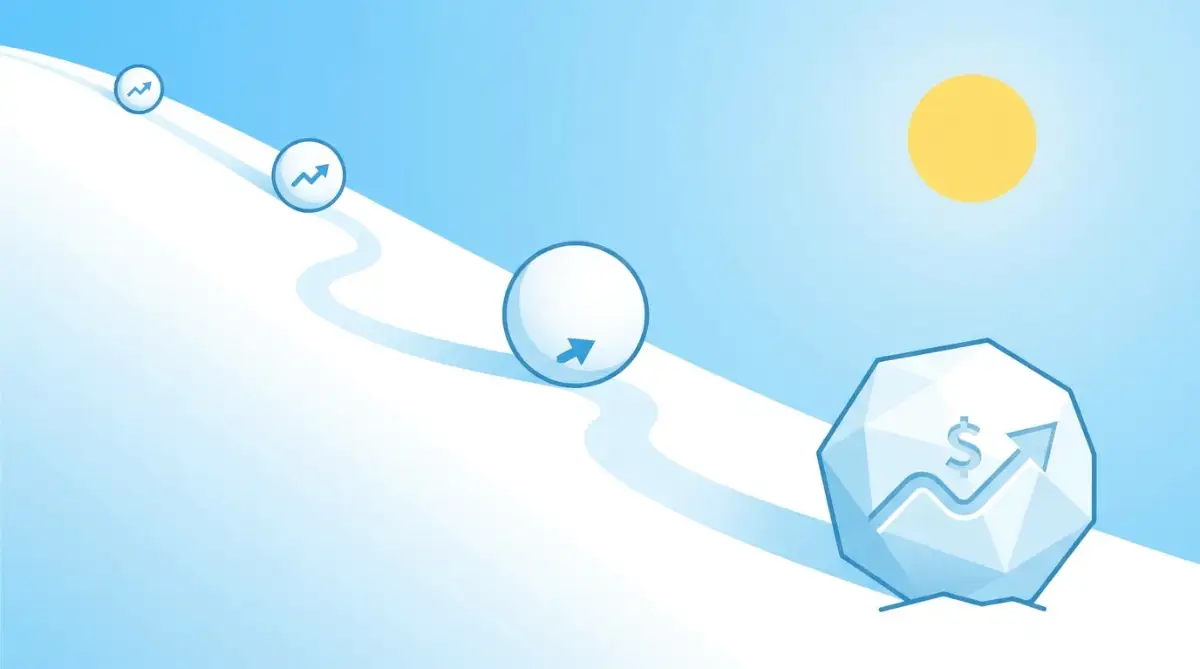
Think of it like rolling a tiny snowball down a very long, snowy hill. The higher up the hill you start, the bigger the snowball gets before it reaches the bottom. If you walk halfway down the hill before dropping the snowball, it simply does not have enough ground to gather maximum size.
Why Tomorrow is the Most Expensive Word
Waiting for the "perfect moment" to get your finances in order is a very dangerous game. Life always finds a way to throw unexpected expenses at you, no matter how carefully you plan.
There will always be a broken car, a leaky roof, or a medical bill that suddenly demands your attention. If you wait for a month where you have zero extra expenses, you will literally be waiting forever.
Taking action today, even with a remarkably small amount, builds a powerful psychological habit. You stop viewing yourself as a spender and slowly begin seeing yourself as an owner of your future.
Emma vs. Noah: A Tale of Two Choices
To truly understand how this delay hurts everyday people, let us look at a completely realistic scenario. Imagine two friends, Emma and Noah, who both want a secure, comfortable life when they stop working.
Emma decides to start putting away just two hundred dollars every single month right now. She sets up an automatic transfer and completely forgets about it, focusing instead on her daily life.
Noah decides he wants to travel a bit more and promises to start saving the exact same amount in exactly five years. He feels confident that he can easily catch up later because five years does not sound like a long time.
By the time they both reach the end of their careers, the final numbers are absolutely shocking. Because Emma gave her money more time to multiply, she ends up with nearly double the amount Noah has. Noah lost hundreds of thousands of potential dollars, simply because he wanted to wait.
The Real Math: Emma vs. Noah (A Quick Look)
Assuming an average 7% annual return.
| Who | Monthly Saving | Years Saved | Total Out of Pocket | Final Wealth at Age 65 |
|---|---|---|---|---|
| Emma | $200 | 40 years |
96,000∣∗∗
96,000∣∗∗
525,000+** |
| Noah | $200 | 35 years |
84,000∣∗∗
84,000∣∗∗
361,000+** |
Notice how just a five-year delay cost Noah over $160,000 in free growth! That is the exact price of waitin
The Heavy Emotional Cost of Catching Up
The financial loss is terrible, but the psychological damage of falling behind is often much worse. When you realize you started late, panic naturally begins to set in.
You suddenly feel immense pressure to take huge risks with your money just to make up for the lost time. People who start late often find themselves working multiple jobs or skipping family vacations out of pure guilt.
They stress over every single market drop and constantly worry if they will ever be able to stop working. Starting early gives you the ultimate luxury in life: a deep, quiet sense of security.
Pro Tip: I used to think I needed hundreds of dollars left over every month before I could even think about investing. My biggest breakthrough happened when I realized I could start with just twenty dollars a week. Building the actual habit of saving was far more powerful for my mindset than the dollar amount itself.
The True Value of Time
"If you want to secure your future, you absolutely must understand how time works in your favor. Watch this incredibly eye-opening breakdown that explains the exact math behind starting today versus starting later."
How to Fix the Problem Starting Today
The absolute worst thing you can do after reading these numbers is to freeze up and do nothing. Feeling guilty about the past will not put a single dollar into your bank account.
You have to accept where you are right now and focus purely on the choices you can make today. You do not need a fancy financial advisor or a complicated spreadsheet to turn this around.
You just need to make a few quick, simple decisions that remove the friction from saving money. Let us look at some highly practical ways you can start moving in the right direction immediately.
Automate Your First Dollar
The biggest mistake people make is waiting to see how much money is left at the end of the month. By the time the final week rolls around, that money has usually magically disappeared into random expenses.
You must flip the script and pay your future self before you pay the grocery store or the streaming services. Set up your banking app to automatically move a specific amount on the exact day your paycheck arrives.
When you never see the cash in your main checking account, you will not even miss it. You will naturally adjust your spending habits to fit whatever is left over.
Hunt Down Silent Money Leaks
Most of us have money quietly draining out of our accounts without us even realizing it. These are usually small, forgotten subscriptions that we signed up for months ago and never use.
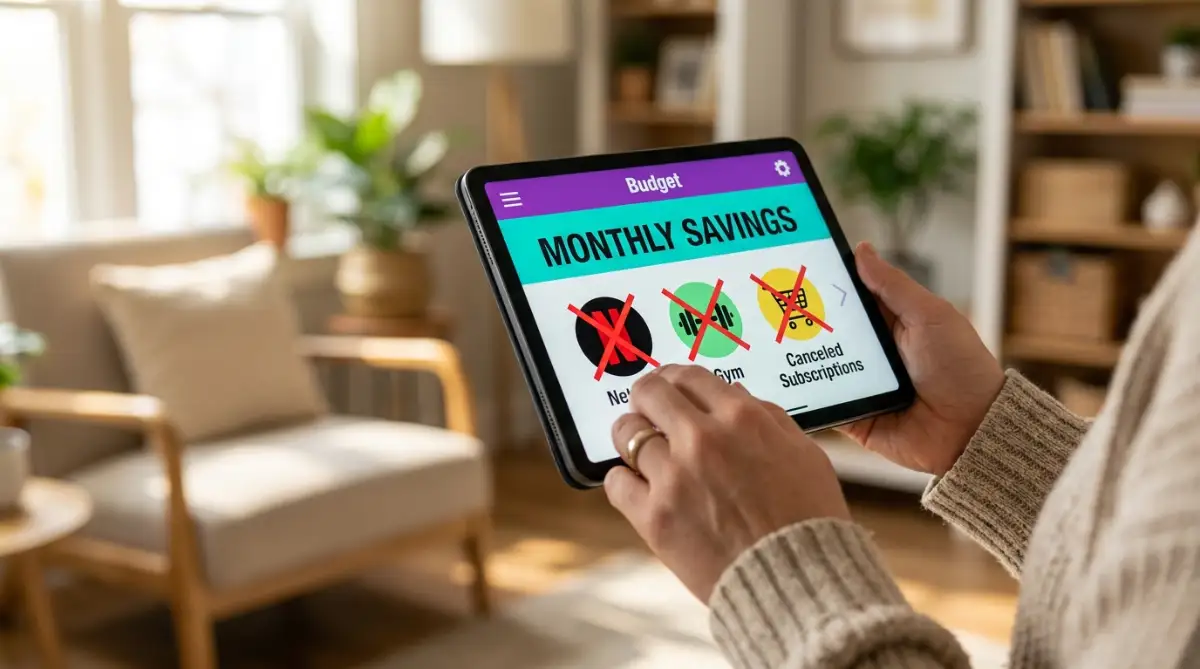
A ten-dollar app here, a fifteen-dollar gym membership there, and suddenly you are losing a hundred dollars a month. Take twenty minutes this evening to sit down with your last two bank statements.
Highlight every single recurring charge that you have not actually used in the past thirty days. Cancel them immediately and automatically redirect that exact amount into your dedicated savings fund.
My Personal Try-This-Today Trick: If digging through bank statements sounds boring, use a free budget tracking app. I connected my checking account to one last year and found out I was still paying $12 a month for a magazine app I deleted in 2021. I canceled it in five minutes and instantly set up a $12 auto-transfer to my savings instead. It takes zero extra effort on my part now.
Turn Unexpected Cash into Future Wealth
Throughout our lives, we occasionally get small bursts of unexpected money. It could be a tax refund, a bonus at work, or even a cash gift for your birthday.
Our natural instinct is to immediately treat ourselves to a nice dinner or a new gadget. While it is perfectly fine to enjoy your life, you need a solid plan for these windfalls.
Try using the "half and half" rule every time unexpected cash lands in your lap. Spend half of it on something fun guilt-free, and send the other half straight toward your future goals.
Myth vs Reality: Clearing the Confusion
There is a lot of terrible advice floating around on social media that tricks people into making bad choices. Let us clear up some of the most common misunderstandings that keep people paralyzed.
Myth: You need to be completely out of debt before you start saving for your older years.
Reality: If you wait until every single loan is gone, you will lose decades of compound growth. You can easily balance paying down debt while simultaneously putting a small amount away for the future.
Myth: Small amounts of money do not make enough of a difference to matter.
Reality: Ten dollars a week might seem useless today, but over time, it grows into a massive safety net. Consistency always beats the actual dollar amount when you add time to the equation.
Changing Your Money Mindset
We often view saving money as a punishment, as if we are locking our hard-earned cash away in a dark room. You have to start seeing it as buying freedom for your older self.
Every dollar you put away today is essentially a small soldier working tirelessly for your future peace of mind. When you change how you look at the process, it completely stops feeling like a chore.
Overcoming the Fear of the Unknown
A major reason we avoid planning for the future is simply because the financial world feels intimidating. There are too many confusing words, charts, and experts shouting conflicting advice at us.
It is perfectly normal to feel scared when you are stepping into a territory you do not fully understand. But ignoring the problem will not make the future go away; it only makes it harder to deal with later.
You do not need to become a Wall Street expert to protect your family and your future. You just need to grasp the absolute basics and stick to a boring, predictable routine.
Finding Hidden Pockets of Cash
If your budget feels incredibly tight right now, you might feel like saving is entirely impossible. However, almost everyone can find tiny pockets of money hidden inside their normal daily routines.
Think about the convenience purchases you make strictly out of habit, rather than actual need. Buying a pre-cut bowl of fruit at the grocery store costs three times as much as buying a whole apple.
Grabbing lunch near the office every single day easily drains hundreds of dollars from your wallet each month. Making small tweaks to your routine frees up cash that can dramatically change your life down the road.
Keep Your Eyes on the Horizon
The journey to financial peace is a marathon, not a quick sprint to the finish line. There will be months where you stumble, face emergencies, and have to pause your progress.
That is just how life works, and you should never beat yourself up over temporary setbacks. The most important thing is that you simply get back on track as soon as the storm passes.
Remind yourself constantly why you are doing this in the first place. You are building a secure wall around yourself so that one day, you can finally relax and breathe easily.
Next-Level Tactics to Multiply Your Wealth Quietly
Once you understand how waiting just a few months can damage your future, the next step is taking massive control. You do not need a fancy finance degree to grow your money securely over time. You just need a few incredibly smart, psychological tricks that keep you on the right path automatically. Let us look at some highly effective strategies that successful people use to build quiet, steady wealth.
These are not get-rich-quick schemes or risky bets on the stock market. These are proven, deeply boring, yet powerfully effective methods that protect your hard-earned money. By setting up these invisible systems, you can completely remove the stress of manual saving from your daily life.
The Magic of the Auto-Escalation Trick
One of the hardest things to do is manually increase your savings rate when your living expenses feel high. Our brains are wired to spend whatever money sits directly in front of us. This is where a brilliantly simple concept called auto-escalation comes into play. You simply make a promise to save a portion of money you do not even have yet.
Whenever you get a raise at work, immediately pretend that half of that raise does not exist. If your paycheck goes up by a hundred dollars a week, adjust your automatic bank transfer to pull out fifty extra dollars. You still get to enjoy a slightly bigger paycheck and improve your current lifestyle. However, you are also massively boosting your retirement fund without feeling any actual pinch in your budget.
According to behavioral research on how automated choices improve financial health, people who use automatic increases end up saving significantly more. They never experience the emotional pain of giving up cash because they never got used to spending it in the first place.
Capturing the Free Money Waiting at Work
It is absolutely amazing how many hardworking people walk past free money every single day. If your employer offers a retirement match program, you must take full advantage of it immediately. A match simply means that if you put a certain amount of your paycheck into savings, your boss will put in their own money too.
If you do not participate, you are literally taking a pay cut by leaving part of your overall compensation package behind. Even if things are extremely tight right now, do everything in your power to contribute enough to get that full match. It is an instant, guaranteed return on your money that you cannot find anywhere else in the world.
The Slow Cooker Approach to Investing
Many people stay away from growing their money because the stock market looks like a terrifying roller coaster. We see news headlines about people losing everything on a bad stock pick, and it scares us away entirely. But true wealth building is not about day trading or watching flashing screens all day long. It is much more like using a slow cooker to make a delicious, hearty soup over many hours.
Instead of trying to pick one winning company, smart savers buy tiny pieces of thousands of companies all at once. This completely spreads out your risk and allows you to capture the overall growth of the entire economy. You put the ingredients in the pot, turn on the heat, and simply walk away and let time do the heavy lifting.
Protecting Your Foundation Before Building the House
You cannot focus on long-term wealth if a flat tire or a broken refrigerator throws you into massive credit card debt. Having a strong safety net is the absolute core foundation of any successful money strategy. Before you aggressively lock your money away for your older years, you must protect your current mental health.
This is why building a cash buffer while fighting debt is such an incredibly powerful move. When you have three to six months of basic living expenses sitting in a separate, easily accessible account, your daily stress vanishes. You can sleep peacefully knowing that if you lose your job tomorrow, your family will still have a roof over their heads and food on the table.
Treating Unexpected Windfalls Like Seeds
Throughout your journey, you will randomly receive small chunks of extra money. This could be a solid tax refund, a holiday bonus, or even selling an old car you no longer need. The natural human reaction is to view this money as a lottery ticket and spend it on an expensive vacation.
While treating yourself is fine, you should view at least half of this money as seeds for your financial garden. If you plant those seeds in your retirement account today, they will grow into massive shade trees for your future. When you combine this habit with regular savings, your wealth begins to snowball much faster than you ever imagined.

The Hidden Pitfalls That Destroy Long-Term Wealth
Knowing what to do is only half the battle when it comes to securing your personal freedom. You also have to know exactly which dangerous traps to avoid along the way. Many smart, hardworking people ruin their financial plans simply because they fall for emotional money mistakes. Let us break down the most common errors that can severely delay your progress.
The Silent Poison of Lifestyle Creep
Have you ever noticed how your expenses somehow perfectly match your income, no matter how much money you make? When we get a better job, we suddenly feel the urge to upgrade our car, buy nicer clothes, and eat at fancier restaurants. This phenomenon is known as lifestyle creep, and it is the biggest reason high earners still live paycheck to paycheck.
You end up looking incredibly wealthy to your neighbors, but behind closed doors, your bank accounts are completely empty. According to reports on the psychological impact of financial stress, living beyond your means causes severe anxiety and ruins relationships. You must build a wall between your increasing income and your desire to buy status symbols to impress strangers.
Raid Now, Cry Later: Touching the Principal
Sometimes life gets tough, and we look at our growing retirement account as an easy escape hatch. People often pull money out of their long-term savings to pay for a child's wedding, a home renovation, or a dream vacation. They tell themselves they will easily pay it back next year when things settle down.
This is a remarkably dangerous move that triggers massive tax penalties and permanently destroys your compound growth. Once you pull that money out, you cannot simply put the lost time back into the equation. Your retirement funds should be placed strictly off-limits, guarded behind a mental wall that you refuse to cross unless it is a literal life-or-death emergency.
Waiting for the Perfect Time to Jump In
A massive mistake beginners make is trying to guess what the economy is going to do next. They read a scary news article and decide to wait until the market looks "safer" before putting their money away. The brutal truth is that nobody actually knows what will happen tomorrow, next month, or next year.
Historically, people who try to time their investments end up performing much worse than those who just invest steadily. Data on market volatility clearly shows that staying invested through the bad times is how you capture the biggest gains during the good times. Stop waiting for clear skies and just start building your financial shelter today.
Buying Houses Without a Complete Plan
Owning property is a wonderful goal, but it can quickly turn into a nightmare if you do not understand the full picture. Many people put every single penny they have into buying a massive house, leaving absolutely nothing left for their daily savings. They become completely "house poor," struggling just to keep the lights on and the property taxes paid.
This completely halts their retirement progress and puts immense pressure on their daily budget. If you are looking to buy property, learning first-time homebuyer strategies can save you from making a tragic mistake. Furthermore, truly understanding your mortgage amortization schedule helps you see exactly how much money is going to the bank versus building your own equity.
Relying Solely on Your Career for Security
We often assume that as long as we have a good job, our future is automatically guaranteed. But companies change, industries shift, and unexpected health issues can suddenly force you to stop working much earlier than planned. If your only plan for the future is simply hoping you can work forever, you are standing on very thin ice.
It is incredibly helpful to research and pick a major for career success if you are just starting out, but your degree alone will not save you. You must actively convert your career income into personal assets that pay you even when you are sleeping. Think of your job as the temporary engine, but your savings account as the actual vehicle that will carry you through life safely.
Your Blueprint for Immediate Financial Relief
You have absorbed a lot of powerful information today, but reading alone will not change your bank balance. The absolute best thing you can do right now is close this screen and take one tiny, positive action. Momentum is an incredible force, and simply setting up one automatic transfer today will instantly make you feel lighter and more in control.
Do not overwhelm yourself trying to fix ten years of financial habits in a single afternoon. Start by simply knowing your numbers, forgiving yourself for any past delays, and looking completely forward. You are the architect of your own future, and today is the perfect day to lay down a brand-new foundation.
Whether you need to review your budget or seek protection for you and your company through proper financial planning, take it one small step at a time. Every dollar you intentionally save today is a gift of freedom you are sending directly to your older self.
My Personal Promise to You: I used to lose sleep constantly, staring at the ceiling and wondering how I would ever catch up on my delayed savings. My biggest win came the day I stopped feeling guilty about my past and finally set up an automatic weekly transfer of just twenty-five dollars. That tiny, simple action completely shifted my mindset, and I promise you that taking your first small step today will bring you that exact same profound peace of mind.
Common Questions About Managing Future Savings
What if I am completely living paycheck to paycheck right now?
Start by tracking exactly where your cash goes for two solid weeks to find hidden leaks. Even saving five dollars a week builds the psychological habit of paying yourself first. Once you build the habit, you can slowly increase the amount as your income grows.
Is it really too late if I am already in my forties?
It is absolutely never too late to take control of your financial direction. While you may have missed some early compound growth, you likely have a higher income now to make larger contributions. Focus on maximizing your current savings rate and ignore the years you cannot get back.
Should I pay off my student loans before saving for my older years?
You should completely avoid pausing your long-term savings just to aggressively pay down low-interest debt. If your employer offers a match, contribute enough to get that free money while making normal payments on your student loans. You need to balance clearing debt with growing your future wealth at the same time.
How do I know exactly how much money I will need when I stop working?
A simple rule is to aim for saving roughly twenty-five times your expected yearly living expenses. Do not let big numbers scare you away from starting right now. Any amount you save will give you far more options and freedom than having nothing at all.
Disclaimer: The information provided in this article is strictly for educational and informational purposes only. It does not constitute financial, legal, or professional advice. Everyone's personal financial situation is completely unique. Please consult with a certified financial planner or qualified professional before making any major decisions regarding your money, investments, or retirement planning.