The Heavy Weight of Multiple Monthly Bills
Look, nobody plans to end up buried in bills. You swipe a card here, take out a quick loan there, and suddenly, you are playing a terrifying game of math just to buy groceries. I get it. But before you panic-search for another magic solution, let's look at a simple, real-world way to combine that mess into one single payment you can actually handle.
Step 2: Fluff Deletion (Reduce Word Count)
Waking up every single day with the heavy burden of multiple loan payments is exhausting. You work incredibly hard for your money, yet by the end of the month, your bank account is completely empty.
You find yourself juggling three credit cards, a personal loan, and a medical bill. Each one has a different due date, a different minimum payment, and a shockingly high interest rate.
Trying to keep track of it all feels like trying to hold water in your hands. This is where understanding how debt consolidation works becomes an absolute game-changer for your financial health.
When you combine all these scattered bills into one single payment, your life suddenly becomes much easier to manage. You stop paying massive amounts of interest to five different banks. Instead, you focus on one clear path toward becoming completely debt-free.
However, many people stay trapped in this stressful cycle for a very long time. They want a way out, but they simply do not know where to start looking for honest advice.
What You Will Learn Today (The Short Version)
- How to find your actual interest rates and see what you really owe.
- The exact differences between using balance transfers and personal loans.
- My weird but effective "ice block" trick to stop spending on cards.
- The top five money traps that keep most people broke even after they consolidate.
Why Finding the Right Solution Feels Impossible
Finding accurate information about money management is surprisingly difficult today. We often search for quick fixes, but the internet is full of confusing advice and hidden traps.
Here is why so many hard-working people struggle to find a real solution:
- Information Overload: You read one article telling you to take out a new loan, and another telling you to cut up all your cards. The conflicting advice leaves you paralyzed.
- Fear of Scams: Many aggressive "debt relief" companies make wild promises about erasing what you owe overnight. These unrealistic claims make people terrified to trust any financial strategy.
- Lack of Financial Education: Schools teach us algebra and history, but nobody sits us down to explain how compound interest works against us.
Myth vs. Fact: The Consolidation Trap
Myth: Consolidating your debt magically lowers how much money you actually owe.
- Fact: You owe the exact same amount! You are just moving it to a cheaper neighborhood (a loan with a lower interest rate) so it grows slower. Do not let shady companies tell you otherwise.
- Shame and Embarrassment: Money struggles are often kept secret. Because people are too embarrassed to ask for help, they rely on unreliable rumors from friends or family.
This lack of clear, actionable guidance leads to very poor decision-making. People often try to borrow money without collateral just to pay off another loan, which only deepens the hole.
The Silent Toll on Your Peace of Mind
The financial damage is only half the story. The real tragedy is what this constant worry does to your everyday happiness.
When your budget is stretched to the breaking point, every aspect of your life takes a hit. Here is how this ongoing struggle slowly destroys your mental peace:
- Sleepless Nights: You lie awake staring at the ceiling, doing endless math in your head about how to cover next week's grocery bill.
- Dread of Unknown Numbers: Every time your phone rings with a number you do not recognize, your heart drops. You assume it is a collector asking for payment.
- Strained Relationships: Money arguments are the leading cause of tension between couples. The constant stress makes you irritable and short-tempered with the people you love most.
- Loss of Confidence: When you feel out of control financially, your self-esteem plummets. You start believing you are simply "bad with money," which is completely untrue.
You deserve to enjoy your life without this constant shadow hanging over you. There is a very clear, logical way out of this mess.
By taking a step back and evaluating your personal loan options, you can build a solid plan to regain your freedom.
The Practical Masterclass: Taking Back Control.
Let us walk through the exact steps you need to take, starting right now.
Step 1: Face the Numbers and Map Your Reality
The very first thing you must do is completely stop hiding from your bank statements. You cannot defeat an enemy you refuse to look at.
I know opening those credit card apps causes a knot in your stomach. However, clarity is the absolute best cure for financial anxiety.
You need to know exactly how much you owe, to whom, and at what price. Grab a simple piece of paper or open a blank spreadsheet on your computer.
Creating Your Master List
Start writing down the name of every single lender you owe money to. Next to the name, write the exact total balance you currently owe them.
Then, find the minimum monthly payment for each account and write that down too. Finally, and most importantly, locate the Annual Percentage Rate (APR) or interest rate for each card or loan.
You will likely be shocked to see rates as high as twenty-five or even thirty percent. Seeing all these numbers in one place might feel scary for a brief moment.
But almost immediately, that fear turns into a sense of immense power. You now have a complete map of the battlefield.
The Reality of High Interest
Let us look at a real-life scenario to make this clear. Imagine you owe five thousand dollars on a credit card that charges twenty percent interest.
If you only make the minimum payment each month, you will end up paying thousands of extra dollars just in interest charges. It could take you over ten years to pay off that single card.
The bank loves this, but it is entirely destroying your ability to build wealth. This is why getting a clear view of your interest rates is the necessary first step toward savings.
Step 2: Choose Your Consolidation Weapon Wisely
Once you know exactly what you owe, you need to find a tool to combine everything. The goal is incredibly simple.
You want to use a single, lower-interest product to completely pay off all the high-interest products. There are two primary ways everyday people successfully do this.
The first method is using a balance transfer credit card. The second method is securing an unsecured personal loan from a bank or credit union.
Quick Comparison: Balance Transfer vs. Personal Loan
If you are feeling confused about whether a balance transfer card or a personal bank loan is better for you, watch this short video to see exactly how both options work. Once you finish watching, keep reading below to discover the sneaky spending traps you need to avoid!
The Balance Transfer Strategy
A balance transfer card is a special credit card that offers an introductory zero-percent interest rate. This promotional period usually lasts between twelve and eighteen months.
You move all your other credit card balances onto this new card. Suddenly, your interest rate drops to zero.
Every single dollar you pay now goes straight toward reducing your actual balance, not into the bank's pockets. However, you must be extremely disciplined.
If you do not pay off the full amount before the promotional period ends, the interest rate will shoot right back up.
The Personal Loan Route
If you have a larger amount of money to pay off, a balance transfer card might not be enough. This is where an unsecured bank loan becomes your best friend.
You borrow a specific lump sum of money at a fixed, lower interest rate. You immediately use this cash to pay off every single one of your high-interest credit cards.
Now, instead of tracking five different bills, you only have one fixed payment every month. You know exactly what day it is due, and you know exactly when the loan will be fully paid off.
It completely removes the guesswork from your monthly budgeting.
Step 3: Stop the Bleeding and Cut the Cords
This next step is where a lot of well-meaning people fail. You just paid off all your credit cards using your new consolidation loan.
Your credit card balances now happily sit at zero. This is a highly dangerous moment for your financial health.
You suddenly have thousands of dollars in available credit limits staring you in the face. The temptation to start spending on those cards again is massive.
Removing the Temptation
If you start using those old cards while still paying off your new consolidation loan, you will end up with double the trouble. You must completely remove the temptation from your daily life.
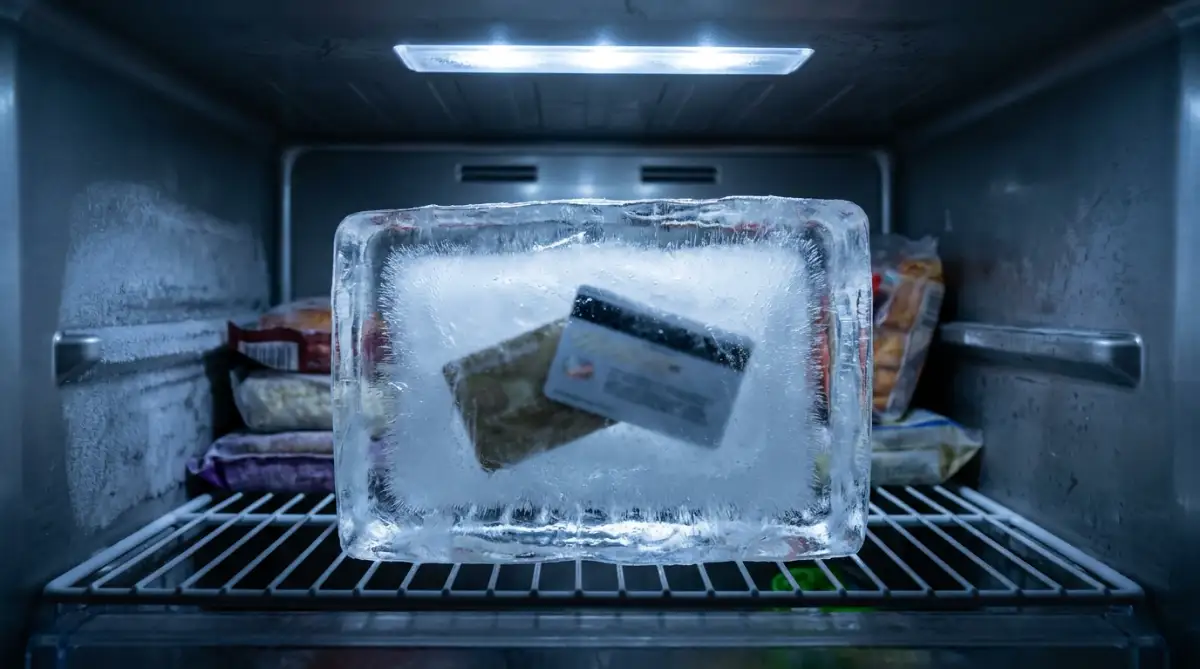
Take those zero-balance credit cards out of your wallet immediately. Put them in a plastic bag, fill the bag with water, and put it in your freezer.
Literally freezing your credit cards forces you to stop and think before making an impulsive purchase online or at the mall.
Deleting Saved Information
You also need to go into your internet browser settings right now. Delete all your saved credit card information from Amazon, food delivery apps, and clothing stores.
When you have to physically get up, walk across the room, and type in your card numbers, you give your brain time to process the decision. You will ask yourself, "Do I really need to buy this right now?"
Most of the time, the answer is no. My absolute biggest mistake was keeping my old credit cards saved on my phone after I paid them off with a new loan. I ended up ordering food online out of pure habit, building up brand new debt right on top of my clean slate! Take it from me: the second you pay off those cards, delete the numbers from every single app immediately so you are not tempted.This simple friction saves you hundreds of dollars every single month.
By following these first three logical steps, you immediately stop the financial bleeding. You take control of the math, secure a better rate, and protect yourself from future mistakes.
But managing your money successfully is a long-term game. In the next section, we will look at some expert-level secrets to ensure you never fall back into this stressful trap
Pro-Level Tactics to Secure Your Financial Future
You have successfully mapped your balances and chosen the right tool to combine them. You have even removed the daily temptation to swipe your cards.
That is an incredible achievement. However, true financial freedom requires a slight change in how you manage your money every single day.
Let us look at a few highly effective expert strategies that will keep your bank account growing steadily month after month.
Step 4: Master the Zero-Based Budget
Consolidating your payments frees up extra cash in your monthly budget. Because your new interest rate is lower, your new single payment is usually much smaller than your old combined payments.
You must give every single one of those saved dollars a specific job. If you just leave that extra money sitting in your checking account, it will magically disappear on random coffees and online shopping.
This is where the zero-based budgeting method becomes incredibly useful.
Giving Every Dollar a Name
Before the new month even begins, you sit down and write out your expected income. Then, you list every single expense you plan to have, including your new combined loan payment.
You subtract your expenses from your income until the final number equals exactly zero. This does not mean you spend all your money until you are broke.
It means every dollar has an assigned purpose, whether it is for groceries, saving for emergencies, or paying extra on your new loan. When you direct your money intentionally, you never have to wonder where it went at the end of the month.
Step 5: Master the Art of Polite Negotiation
Most people completely forget that they can actually talk to their banks. They assume that whatever interest rate the computer spits out is final.
This is a massive missed opportunity to save even more money. Before you accept the very first consolidation offer you receive, take a moment to negotiate.
If you have a decent history of making payments on time, you hold a lot of power. You can often access exclusive bank loans with much better terms just by asking the right questions.
How to Talk to Lenders
Call the customer service department of your local bank or credit union. Politely tell them you are shopping around for the absolute best rate to combine your current balances.
Mention that another lender offered you a specific, low percentage rate. Ask them directly if they can beat that number to win your business.
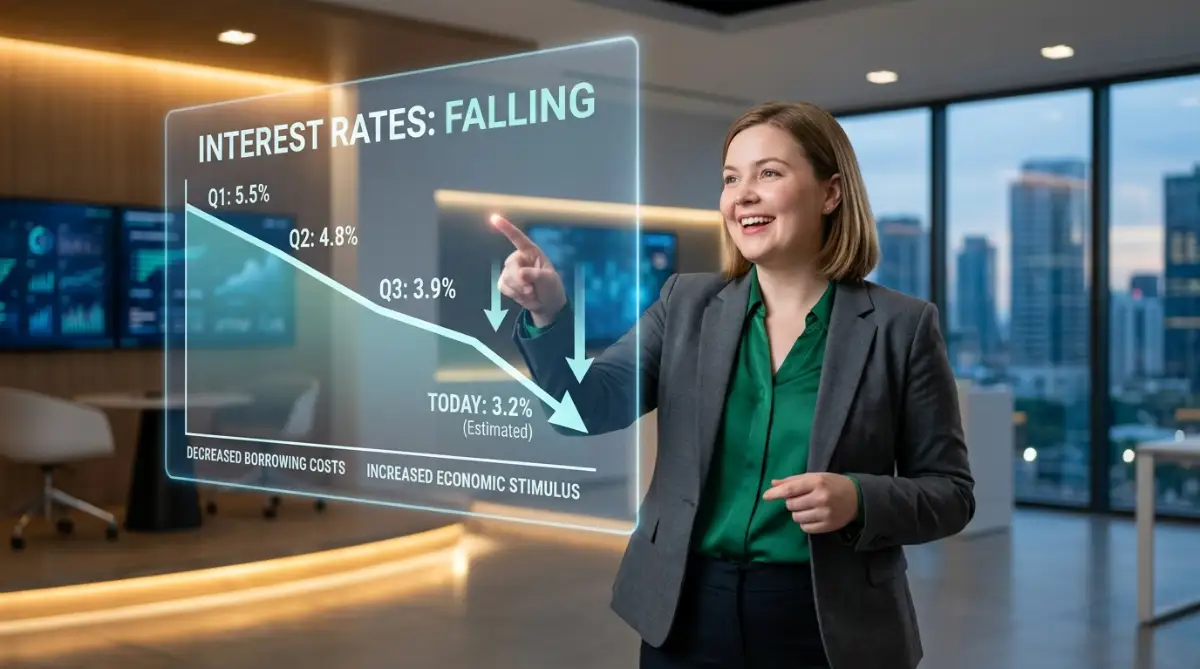
You would be amazed at how often a bank representative will lower your rate just to keep you as a customer. Even a one percent drop in your interest rate saves you hundreds of dollars over the life of your loan.
Dangerous Traps You Must Avoid at All Costs
The path to becoming completely debt-free is simple, but it is not always easy. Human psychology often gets in the way of our logical plans.
Many people start out with great intentions but quickly fall into hidden financial traps. If you want to successfully save money long-term, you must actively avoid these five common mistakes.
1. Treating the New Loan as "Free Money"
The absolute biggest mistake people make is feeling rich as soon as their old credit cards are paid off. They see zero balances and suddenly think they have extra money to spend on vacations or new gadgets.
They forget that the original balance did not disappear; it just moved to a new home. You must remember that a consolidation loan is a tool for recovery, not an excuse for a shopping spree.
2. Stretching the Timeline Too Far
When you apply for a new personal loan, the bank might offer you a five or seven-year repayment plan. The monthly payment on a seven-year plan looks wonderfully cheap.
However, this is a massive math trap. By stretching the loan out for so many years, you end up paying far more total interest than you originally owed. Always choose the shortest repayment timeline you can comfortably afford.
3. Ignoring the Root Cause of the Spending
Consolidation treats the symptom, but it does not cure the actual disease. You have to ask yourself honestly why you ran up so many credit cards in the first place.
Was it an unexpected medical emergency, or was it a habit of buying things to feel happy? If you do not fix the underlying spending behavior, you will absolutely end up in the exact same financial mess within a few months.
4. Falling for Predatory Relief Scams
If you ever hear a company promise to "legally erase" your balances for an upfront fee, run away immediately. These scam artists prey on vulnerable people who are desperate for a quick fix.
Legitimate consolidation involves you taking out a real loan to pay your actual creditors. You should never have to pay a massive upfront fee just to get basic help managing your own bills.
5. Immediately Closing All Old Accounts
After paying off a frustrating credit card, your first instinct is to call the bank and cancel the card entirely. Surprisingly, closing old accounts can actually hurt your credit score.
Your credit score is heavily based on your total available credit limit and the length of your credit history. Instead of closing the accounts, just cut up the physical plastic cards and leave the accounts open with a zero balance.
Your Fresh Start Begins Today
Managing your money does not have to be a source of constant fear and anxiety. You now have a complete, highly practical roadmap to simplify your entire financial life.
By gathering your balances, securing a lower interest rate, and protecting yourself from future spending, you instantly take back control. The math is completely on your side once you remove those punishing twenty-five percent interest rates.
Imagine waking up next month and only having to write one single check. Imagine watching your principal balance actually go down every time you make a payment.
That feeling of relief is completely within your reach right now. You do not need to wait for a miracle to fix your budget.
I promise you that the heavy weight on your chest will disappear the moment you make your first combined payment. You are not a bad person just because you got into debt, and you absolutely have the power to turn your financial life around today. Take a deep breath, trust the process, and take that very first step toward your freedom right now.
Grab a pen, log into your bank accounts, and write down your numbers today. You have the knowledge, you have the strategy, and you are entirely capable of building a wealthy, stress-free future for yourself.


