Waking Up to a Zero Balance: The Silent Struggle We Rarely Talk About
Ever checked your banking app on a random Tuesday morning, saw a $3 balance, and realized payday is still five agonizing days away? Yeah, that sinking feeling in your stomach is all too real. You work hard, put in honest hours, and somehow still end up running on empty by the end of the month. It is exhausting, but you are absolutely not broken or bad with money. Let's look at exactly how to plug the hidden leaks in your bank account and fix this exhausting cycle today, step by step.
I was working a full-time job, putting in honest hours, yet I always felt like I was running on a never-ending treadmill. No matter how hard I tried, my bank account always hit zero right before the next direct deposit came in. I felt trapped, exhausted, and honestly, a little embarrassed that I could not figure out my own money.
This is the hidden reality for so many hard-working people today. You wake up early, you give your best energy to your employer, and you try to do everything right. Yet, the reward feels entirely disconnected from the effort you put in.
You find yourself doing mental math in the grocery store aisle, hoping your debit card does not decline at the checkout counter. This constant state of financial survival mode steals your peace of mind and forces you to live in fear of tomorrow. You are not alone in this feeling, and you are not broken because you are struggling right now.
But the truth is, making more money rarely solves the problem if the underlying foundation is broken. I learned the hard way that without a clear system, an increase in income only leads to an increase in spending. You deserve to sleep peacefully at night without wondering how you will pay next month's electric bill.
Quick Takeaways: What You Need to Know
- Print your bank statements and physically circle your non-essential spending.
- Force yourself to wait 48 hours before buying anything online over $20.
- Calculate your "bare-bones" budget so you know exactly what you need just to survive.
- Build a quick $500 safety net before trying to tackle massive debts.
- Treat your savings like a fixed bill and move the money the second you get paid.
Rethinking the Rules: How to Actually Break the Cycle
To fix a problem this deep, we have to completely change the way we interact with our money on a daily basis. The advice to "just spend less" is completely useless if you do not have a practical framework to follow. We need realistic strategies that work for regular people who have actual bills to pay.
Most financial advice assumes you have hundreds of extra dollars lying around to invest, which is not helpful when you are struggling to buy dinner. We are going to focus on small, highly effective shifts that slowly give you back your power. Let’s look at the exact steps you can take today to slowly walk away from this exhausting cycle.
Stop the Invisible Money Leaks First
Before you can build wealth, you have to find out exactly where your hard-earned money is disappearing to. You might think you know where your cash goes, but our brains are very bad at tracking small, frequent purchases. Those three-dollar coffees and spontaneous online purchases blend together until they eat up hundreds of dollars.
The very first action you must take is printing out your last 30 days of bank statements. Grab a red pen and physically circle every single transaction that was not essential for your survival. Do not judge yourself during this process; just look at the raw data in front of you.
You will quickly notice a pattern of "invisible spending" that happens when you are bored, stressed, or tired. Maybe it is grabbing fast food on the way home because you are too exhausted to cook. Once you see these patterns clearly on paper, you take away their power over your wallet.
You can then make a conscious decision to block these specific triggers moving forward. If you always buy snacks at the gas station, start keeping a box of protein bars in your car. This is not about punishing yourself, but about plugging the holes in your financial bucket.

The 48-Hour Cooling-Off Strategy for Online Spending
One of the biggest traps keeping people broke is the extreme convenience of modern digital shopping. With saved credit card details and one-click buying options, it takes less than five seconds to spend money. This removes the emotional weight of handing over physical cash, making it dangerously easy to overspend.
To counter this, you need to introduce artificial friction into your buying habits. Implement a strict 48-hour cooling-off rule for any non-essential purchase over twenty dollars. When you see something you want to buy, add it to your cart, but close the browser immediately.
Are you struggling to stick to a budget because it feels too restrictive? Watch this amazing breakdown of how to build a flexible money plan that actually works for normal people. This simple method will completely change how you view your monthly income.
During those 48 hours, your initial emotional excitement will slowly fade away. You will find that your logical brain steps in and asks if you truly need this item right now. Nine times out of ten, you will completely forget about the item or decide it is not worth your money.
This single habit can easily save you hundreds of dollars a month withou
t making you feel deprived. It puts a solid wall between your impulses and your bank account, giving you time to think.
Structuring a Realistic "Bare-Bones" Survival Plan
If you want to stop running out of money, you need to know exactly how much it costs simply to keep you alive and safe. We call this your bare-bones budget, and it is the most important number in your entire financial life. This number only includes your rent, basic utilities, essential groceries, and the transportation needed to get to work.
It absolutely does not include eating out, entertainment subscriptions, new clothes, or hobbies. You need to calculate this exact number so you know your minimum monthly survival baseline. Once you have this number, anything you earn above it is your actual disposable income.
When things get tough, or you face an unexpected expense, you immediately revert to this bare-bones plan. It gives you a sense of extreme clarity and removes the panic of wondering what to cut out. You already know what your absolute essentials are, so you can easily strip away the rest temporarily.
Quick Comparison: Bare-Bones vs. Normal Monthly Budget
| Expense Category | Regular Budget | Bare-Bones Survival Plan |
| :--- | :--- | :--- |
| Food | $500 (Includes takeout & coffee) | $250 (Basic groceries only) |
| Subscriptions | $60 (Netflix, Spotify, Gym) | $0 (Cancel or pause all) |
| Transportation | $150 (Gas + weekend trips) | $80 (Work commute gas only) |
| Housing & Utilities| $1,200 (Rent + fast internet) | $1,200 (Non-negotiable) |
I recommend writing this number on a sticky note and placing it somewhere you will see it often. It serves as a strong reminder that you do have control over your baseline living expenses.
The Pro Tip: My "Cash Only" Grocery Run
I spent years going over my grocery budget because I would mindlessly toss extra snacks and items into my cart while shopping. I finally found a trick that worked perfectly for me: I started leaving my debit card at home and only bringing exact cash to the supermarket. The anxiety of potentially not having enough money at the checkout register completely stopped me from buying useless junk. This simple physical boundary forced me to stick entirely to my prepared shopping list.
Building the Starter Safety Net
The main reason people stay trapped in a paycheck-to-paycheck cycle is the lack of a financial shock absorber. Life is incredibly messy, and things will inevitably break, get lost, or require urgent medical attention. If you do not have a buffer, every single emergency goes straight onto a high-interest credit card.
You do not need a massive six-month emergency fund right away; that goal is too big and discouraging for beginners. Your only goal right now is to save up a beginner buffer of exactly $500. This small amount of money is enough to cover minor car repairs, an urgent doctor visit, or a sudden bill.
To get this $500 quickly, look around your house for things you no longer use and sell them online. Cancel all of your subscription services for just one month and put that money directly into a separate savings account. Do whatever it takes, safely and legally, to build this tiny wall of protection as fast as humanly possible.
Having this cash sitting in a separate account changes your entire psychological approach to money. You will walk a little taller knowing that a flat tire will not completely ruin your week.
Myth vs Reality: The Budgeting Trap
There are so many misconceptions about managing money that actively push people away from trying. Let’s break down a few common myths that might be holding your progress back.
Myth: Budgeting means you can never have any fun or buy things you enjoy.
Reality: A budget is simply a plan that gives you permission to spend money on things that actually matter to you. It prevents you from wasting cash on things you do not care about.
Myth: I do not make enough money to save anything right now.
Reality: Saving is a habit, not an amount. Even saving five dollars a week builds the mental muscle required to manage larger amounts of wealth later on.
Myth: I will start managing my money when my debts are fully paid off.
Reality: You cannot successfully pay off your debt unless you are actively managing your daily spending habits first.
Designing a "Pay-Yourself-First" System
One of the biggest mistakes we make is paying all our bills, spending money on lifestyle choices, and then trying to save whatever is left over. The harsh reality is that there is rarely anything left over by the end of the month. Human nature always finds a way to spend available resources.
To beat this natural tendency, you must reverse the entire process immediately. The moment your paycheck hits your bank account, transfer a specific percentage directly into your savings account before doing anything else. Treat this savings transfer exactly like a non-negotiable electric bill or rent payment.
Start incredibly small if you need to, perhaps just transferring twenty dollars per paycheck. The amount does not matter in the beginning; the automation of the habit is what creates long-term success. Over time, you can slowly increase this amount as you get more comfortable with your new spending limits.
When you remove the money immediately, your brain automatically adjusts to living on the remaining balance. You learn to make things work with what is visible in your main checking account. This automatic system protects your future self from your current spending impulses.
Increasing the Gap Between Income and Outflow
Ultimately, breaking this stressful cycle comes down to basic math. You must widen the gap between what you earn and what you spend every single month. You can do this by aggressively cutting your expenses, but there is a physical limit to how much you can cut before life becomes miserable.
The other side of the equation is finding creative ways to increase your income, even temporarily. You could pick up a few freelance gigs online, offer to work overtime at your current job, or start a small weekend side hustle. The extra money you make from these efforts should not be used to upgrade your lifestyle.
Every single extra dollar you earn must be assigned a specific job, whether that is funding your safety net or paying down a credit card. If you do not assign the extra money a job, it will easily slip through your fingers on random dinners out.
Think of your extra income as a powerful tool to buy back your future freedom. It takes a lot of discipline to work extra hours and save the money, but the peace of mind you gain is absolutely worth the effort. You are essentially trading short-term comfort for long-term stability and happiness.
Mastering the Art of Delayed Gratification
Our society constantly pushes us to buy things instantly to feel better about ourselves. We are bombarded with targeted advertisements that promise happiness if we just swipe our credit cards. Escaping the paycheck-to-paycheck cycle requires you to consciously reject this culture of instant gratification.
When you delay a purchase, you are not saying "no" to yourself forever. You are simply saying "not right now" so that you can secure your financial foundation first. It is about choosing what you want most in life over what you want in this exact moment.
Learning to wait gives you immense power over your financial destiny. You will start to appreciate the things you do buy much more because you patiently saved and planned for them. This mindset shift is what separates people who struggle financially from those who build lasting wealth and peace.
Leveling Up Your Money Game: Insider Strategies
Once you master the basics of tracking your spending, it is time to move to the next level of money management. You need a proactive system that automatically works in the background of your daily routine. This takes the heavy mental lifting off your shoulders and turns good habits into an automatic reflex.
One of the most powerful methods professionals use is called the zero-based allocation method. Instead of just guessing what you will spend, you assign a specific job to every single dollar before the month even begins. Think of yourself as a boss assigning specific tasks to your employees; no dollar is allowed to sit around doing nothing.
Some dollars go to work paying the electricity bill, while others are assigned to buy groceries or fund your savings account. When your income minus your expenses equals exactly zero, you know you have perfectly planned your entire month. If you have fifty dollars left over, you must actively assign it to a savings goal or debt payment.
The Paycheck Syncing Technique
A massive reason people run out of money is poor cash flow timing, not necessarily a lack of income. You might make enough money overall, but if all your major bills are due in the first week of the month, you will struggle. This creates a feast-or-famine situation where you feel rich on the first day and completely broke by the seventh.
To fix this, you must strategically sync your bill due dates with your specific pay schedule. Call your credit card companies, internet provider, and utility services to request a change in your billing cycle dates. Most major companies are surprisingly happy to adjust your due dates if you simply ask a customer service representative.
By splitting your heavy bills evenly between your first and second paychecks of the month, your cash flow remains smooth. You will no longer experience that terrifying dip in your checking account during the middle of the month. This one phone call can completely remove the week-to-week anxiety of paying your basic living costs.
Setting Up Sinking Funds for Hidden Expenses
We often get completely derailed by expenses that we know are coming but pretend do not exist. I am talking about things like annual car registrations, holiday gifts, or back-to-school supplies for your children. Because these are not regular monthly bills, they always feel like a shocking emergency when they arrive.
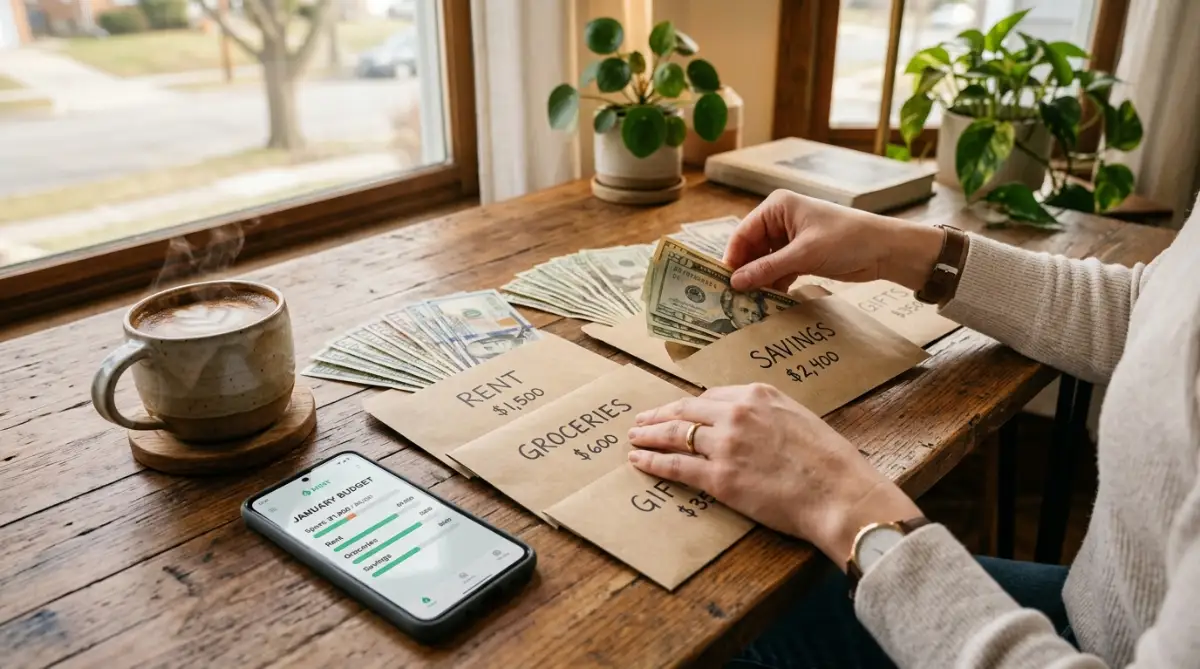
The secret to handling these hidden costs is setting up targeted sinking funds in your bank account. You simply take the total estimated yearly cost of an event and divide it by twelve months. If you know you will spend six hundred dollars on holiday gifts, you need to save fifty dollars every single month.
When the holidays finally roll around, you simply transfer the cash from your sinking fund and buy what you need. There is zero panic, zero guilt, and absolutely no new credit card debt hanging over your head. If you are serious about building a cash buffer to fight debt, treating irregular expenses as monthly bills is a guaranteed game-changer.

Negotiating Your Fixed Living Costs
Many people wrongly assume that their monthly bills are set in stone and cannot be changed. In reality, the modern consumer market is highly competitive, and companies want to keep your business at almost any cost. You have incredible power as a paying customer, but you have to be willing to pick up the phone.
Spend an hour reviewing your auto insurance, mobile phone plan, and internet service provider costs. Look up current promotional rates for new customers and ask your current provider to match those exact prices. According to resources from the Consumer Financial Protection Bureau (CFPB), regular negotiation is one of the easiest ways to lower household expenses without changing your lifestyle.
The 60-Second Negotiation Script
Not sure what to say on the phone? Try reading this exact script when you call your internet or phone provider:
"Hi there, I've been a loyal customer for a few years now, but my bill has gotten a bit too high for my current budget. I noticed [Competitor's Name] is offering a similar plan for $40 a month. Before I go through the hassle of switching, are you able to match that rate for me today?"
It works like a charm almost every single time!
If your current provider refuses to lower your rate, politely inform them that you are going to cancel your service. They will almost always transfer you to a retention department that has the authority to offer you massive discounts. Saving just fifty dollars a month on your internet bill puts six hundred dollars back into your pocket over twelve months.
The Hidden Traps That Keep You Broke
Even with a perfect plan on paper, human psychology often gets in the way of our financial success. We tell ourselves little lies to justify bad spending habits, and these lies slowly drain our bank accounts. Recognizing these emotional traps is the only way to stop falling into them month after month.
The "I Deserve It" Emotional Trap
This is arguably the most dangerous mindset you can have when trying to escape financial stress. After a remarkably hard week at work, your brain tries to convince you that you deserve a costly dinner or a new gadget. You trade your long-term financial security for a fleeting moment of comfort that lasts maybe an hour.
The truth is, you absolutely do deserve good things in life, but you also deserve to live without crushing money anxiety. When you spend money emotionally, you are actually punishing your future self just to comfort your present self. True self-care is having enough money in the bank to sleep peacefully, not buying a temporary distraction.
If you constantly rely on borrowed money to fund these emotional purchases, you are stepping into dangerous territory. You might eventually find yourself needing to learn about getting a bank loan without collateral just to consolidate the mess. Break the cycle now by finding free or low-cost ways to reward yourself after a long week.
Falling Victim to Lifestyle Creep
Have you ever noticed that as soon as you get a raise at work, your expenses magically increase to match it? This silent wealth killer is known as lifestyle creep, and it is the reason high-income earners can still be completely broke. You start upgrading your car, buying name-brand groceries, and eating at fancier restaurants simply because you can.
Instead of using the extra income to secure your future, you inflate your daily lifestyle until you are right back to zero. To avoid this trap, you must pretend that your raise or bonus never actually happened. Continue living on your previous income level and automatically route the new money directly into investments or debt reduction.
This requires serious mental discipline because society expects you to show off your success with material items. However, the Federal Trade Commission's financial guides consistently show that living below your means is the true path to independence. True wealth is the money you do not spend, not the fancy items you display to your neighbors.
Ignoring the Power of Small Numbers
When we look at our massive financial goals, it is easy to get discouraged by our slow progress. We look at our goal of eventually mastering a first-time property purchase and think a ten-dollar savings deposit is useless. This dangerous mindset tricks you into spending that ten dollars on junk because it feels too small to matter.
Every single massive fortune in the world was built one small dollar at a time over a long period. When you respect the small numbers, the big numbers naturally take care of themselves. Skipping a daily fancy coffee might seem pointless today, but that consistent habit builds the discipline required to manage a mortgage later.
Never underestimate the compounding power of small, consistent positive actions over a long timeline. A small river slowly cuts through solid rock not because it is powerful, but because it is persistent.
Your Action Blueprint for Complete Financial Peace
Reading about money management will not change your life unless you actually take physical action today. We are going to break your transition down into a simple, manageable timeline that feels completely achievable. Do not try to fix everything at once; just focus on winning the very next step in front of you.
Day 1 to Day 7: The Awareness Phase
Your only job this week is to track every single penny that leaves your hands without making any major changes. Carry a small notebook or use a free app on your phone to log your purchases immediately. You need raw, honest data about your current reality before you can start fixing the leaks.
Day 8 to Day 14: The Cutting Phase
Now that you see your spending patterns, go through your bank statements and ruthlessly cancel unused subscriptions. Call your insurance providers and internet companies to negotiate better monthly rates using the scripts we discussed. Put all the money you save directly into a separate account to jumpstart your beginner safety net.
Day 15 to Day 30: The Growth Phase
Start looking for small ways to increase your income streams outside of your primary job. If you decide to start a side hustle, make sure you learn about launching your business without failing before investing your money. Whether you are driving for a delivery app or selling old items, every extra dollar should go straight toward building your financial buffer. As your income grows, you might also want to explore navigating the legal system for safe protection to ensure your new side income is secure.
The journey to financial freedom is rarely a perfectly straight line, and you will make a few mistakes along the way. Be gentle with yourself when you mess up, but never use a small mistake as an excuse to completely quit. Keep pushing forward, and you will eventually wake up to a bank account that brings you total peace of mind.
I spent years feeling suffocated by my own bank account, thinking I would never figure it out. Once I finally took control and followed these exact steps, my entire world opened up in ways I never imagined. You have the exact same power to rewrite your financial story starting this very minute.
Real Questions People Ask About Breaking the Broke Cycle
Why do I always run out of money before payday?
You likely suffer from a lack of intentional planning and invisible spending leaks. Without a clear plan, small daily purchases quickly drain your account before your major bills are even paid. Creating a bare-bones spending plan helps you easily identify and plug these hidden cash leaks.
How can I save money when my bills are higher than my income?
If your basic survival bills truly exceed your total income, you are facing a severe math problem, not just a behavior problem. You must aggressively lower your housing or transportation costs while simultaneously seeking a second income source. You cannot simply budget your way out of a true income deficit; you have to increase your earning power quickly.
Is it normal to live paycheck to paycheck?
Yes, unfortunately, it has become incredibly common for the majority of working-class adults today. According to regular surveys by the Bureau of Labor Statistics (BLS), a massive percentage of consumers spend almost exactly what they earn. However, just because something is considered normal does not mean you have to accept it for your own life.
What is the 50 30 20 rule in budgeting?
This is a popular method where you spend fifty percent of your money on absolute needs like rent and food. You then spend thirty percent on wants like hobbies or dining out, and save the final twenty percent for the future. It is a fantastic starting point for beginners who want a simple, flexible framework to manage their cash.
Should I pay off debt or build my savings first?
You must always save a small, basic safety net of roughly five hundred dollars before attacking your debts. If you have no cash savings, your very first emergency will force you to use a credit card, putting you right back into debt. Once your basic buffer is secure, you can throw all your extra cash at your high-interest balances.
Disclaimer: The content provided in this blog post is for informational and educational purposes only and should not be construed as professional financial advice. Every individual's financial situation is unique. Please consult with a certified financial planner or professional advisor before making any major financial decisions, investments, or changes to your debt management strategies.