The Daily Nightmare of the "Single Bank Account" Trap
Let us be completely honest—keeping all your money in one single checking account is a massive trap. You look at your bank balance, feel rich for about five seconds, and then the panic hits. You suddenly realize you have no idea how much of that cash is safe to spend on weekend pizza, and how much needs to stay untouched for Tuesday's electric bill. I finally fixed this endless money stress by doing the exact opposite of what most traditional banks suggest: I opened more accounts.
I would stare blankly at my banking app, doing mental math to subtract my upcoming rent, groceries, and utility bills. Inevitably, my brain would forget about a random software subscription or a quarterly insurance payment. I ended up spending money I needed for my fixed bills on eating out with friends.
This simple mistake led to accidental overdrafts, immense emotional stress, and a constant feeling that I was failing at being an adult. My money was just one giant, confusing mess..
Having just one place for all your cash creates a confusing "money soup" where your rent money mixes with your coffee money. It completely destroys your mental peace because you are forcing your brain to remember a dozen different upcoming expenses at once.
The hard truth is, managing your personal wealth should not require a calculator and a panic attack every time you want to buy lunch. We naturally think that having fewer accounts means less work, but the exact opposite is true.
When you dump all your resources into one single bucket, you set yourself up for failure. You lack clarity, you lack boundaries, and you lack the financial security that comes from proper organization.
Quick Takeaways for Your Wallet:
- Stop mixing your rent money with your coffee money in one giant, confusing pool.
- Use a central "Hub" for your paycheck, then immediately send cash to specific "Spokes" (Bills, Fun, and Savings).
- Keep your emergency vault at a completely different bank so you do not randomly spend it.
- Automate your bank transfers on payday so you never have to do the math manually again.
How Separating Your Cash Rewires Your Brain for Success
Most of us were taught to open one checking account for daily use and maybe one savings account if we were lucky. But relying on this outdated method is like serving an entire dinner party from a single, giant mixing bowl.
Everything gets mashed together, making it impossible to separate the main course from the dessert. When it comes to your finances, this lack of separation is exactly what ruins your monthly budget.
By strategically opening a few different accounts, you give every single dollar a very specific job. This completely removes the emotional guesswork from your daily spending habits.
You no longer have to check your balance and wonder if you can afford to go to the movies. If the money is in your fun account, you can spend it without a single ounce of guilt or fear.
 The Psychology Behind Mental Accounting
Behavioral scientists have a term for how humans categorize their resources, and they call it mental accounting. We naturally want to put things into neat little boxes in our minds to understand them better.
When your bank setup actually matches the way your brain works, managing your budget becomes incredibly easy. You stop fighting your natural habits and start using them to your advantage.
If you see a large balance in a single account, your brain automatically assumes you have plenty of disposable income. This visual trick encourages you to overspend on things you do not actually need.
However, if you only see $150 in your dedicated spending account, your brain instantly recognizes your true limits. You automatically adjust your behavior without needing extreme willpower or complicated spreadsheets.
Breaking Down the Hub and Spoke Strategy
The most effective way to fix a broken financial system is to use a method experts call the Hub and Spoke strategy. Imagine a bicycle wheel, where the center hub connects all the outer parts together.
Your main income account acts as this central hub where your paycheck lands first. From there, the money flows outward to specific spokes, which are your other accounts.
You do not keep any money in the hub account long-term. It is simply a sorting center to process your income before it gets sent to its correct destination.
This creates a smooth, predictable system that practically runs itself once you set it up properly. Let us look closely at exactly what these outer spoke accounts should be.
A Real-Life Monthly Flow (Example Setup)
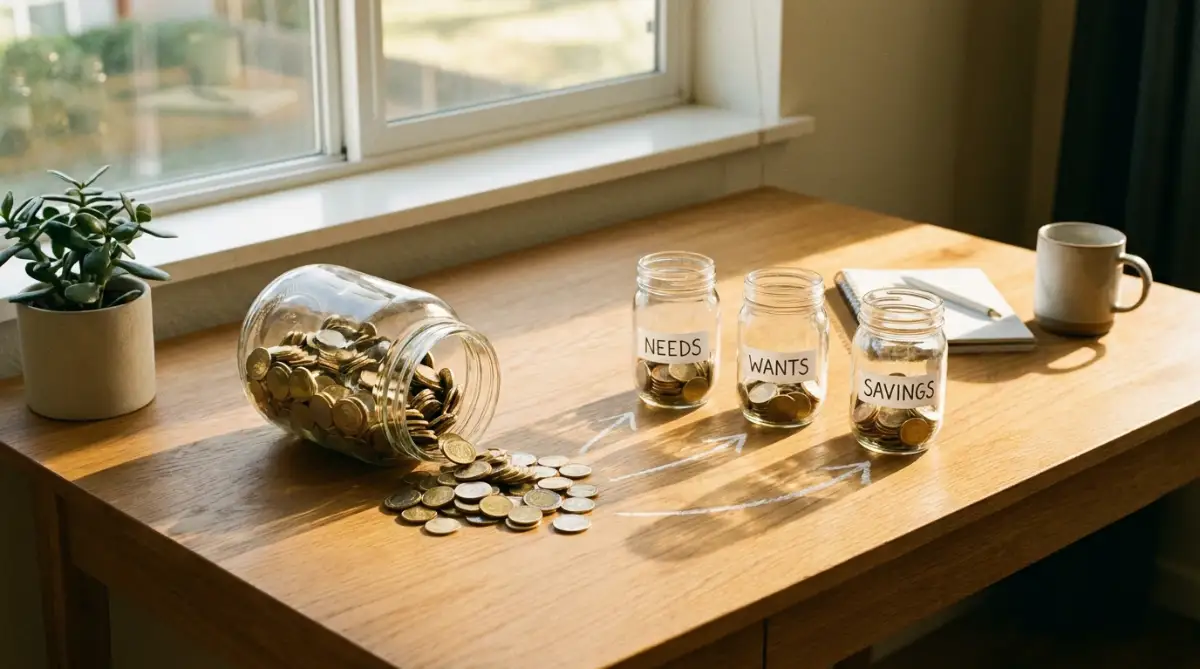
If you are wondering how this actually looks in practice, here is a quick breakdown of how you can route a standard $4,000 monthly income using this exact system:
Spoke #1: The Fixed Bills Control Center
This is arguably the most important bank account you will ever open in your entire life. Think about all the non-negotiable expenses you absolutely must pay every single month.
This includes your housing costs, electricity, internet, cell phone, and minimum debt payments. These are the bills that keep a roof over your head and the lights turned on.
You should calculate the total amount needed for these bills and transfer that exact amount into this dedicated account. You should never, under any circumstances, use a debit card linked to this account for everyday shopping.
By building a protective wall around your bill money, you guarantee your most important obligations are always met. You will never again experience the stomach-dropping fear of a bounced rent check.
Spoke #2: The Guilt-Free Spending Zone
This is the account that makes sticking to a budget actually fun and sustainable long-term. Depriving yourself of everything you enjoy is a guaranteed way to fail at managing your cash.
You need a specific place designated purely for your lifestyle expenses, like dining out, hobbies, and entertainment. Once you have funded your bills and your savings, a portion of your money goes straight into this account.
When you go to a restaurant, you only use the debit card attached to this specific spending account. If the card gets declined because you ran out of funds, you simply wait until your next payday.
There is immense freedom in knowing you can spend every single penny in this account without ruining your financial life. It removes the shame from buying a coffee and lets you actually enjoy your hard-earned money.
Here is a small secret that completely changed my perspective on managing cash. I realized that my biggest mistake was keeping my emergency savings in the exact same banking app as my daily checking account. Moving that emergency cash to a completely different bank removed the temptation to dip into it for random weekend shopping, saving me from myself on multiple occasions.
If you are a visual learner, this detailed breakdown perfectly explains how to structure your accounts for maximum peace of mind. Check it out below before setting up your own system.
Spoke #3: The "Do Not Touch" Emergency Vault
Life is completely unpredictable, and financial emergencies will happen to you eventually. Your car might break down, your roof might leak, or you might face unexpected medical bills.
This is why you absolutely need a separate savings account that acts as a financial shock absorber. However, this account should ideally be kept at a completely different institution than your daily checking accounts.
When your savings are out of sight, they are out of mind, making you much less likely to steal from yourself. If you have to wait three days for a bank transfer to clear, you will rarely make impulse purchases with that money.
Why People Resist the Multi-Account System
Whenever I explain this strategy to my friends, they usually respond with the exact same objection. They think managing four different bank accounts sounds like a massive administrative nightmare.
They imagine spending hours every week logging into different websites and transferring pennies around manually. But they are completely missing the incredible power of modern financial technology.
Today, you do not have to move your money manually if you do not want to. You can automate almost every single part of this entire process, turning it into a passive machine.
Once the initial setup is complete, maintaining this system takes maybe ten minutes of your time per month. The initial effort you put in pays off with years of financial clarity and zero stress.
The Magic of Automatic Money Flow
The easiest way to fuel your different accounts is to use your employer's direct deposit system. Most payroll departments will gladly split your paycheck into multiple different bank accounts for you automatically.
You can ask them to send your bill money to one account, your savings to another, and the rest to your spending account. Before you even wake up on payday, your money is completely organized and ready to go.
If your employer cannot split your deposit, you can easily set up automatic transfers within your banking app. You just tell the system to move specific amounts on the exact days you get paid.
This automation protects you from your own lazy habits or emotional spending triggers. The right choices happen automatically in the background while you focus on living your life.
Myth vs Reality: The Multi-Account Strategy
There are a lot of misconceptions floating around the internet about having multiple banking relationships. It is time to clear the air so you can make confident choices about your personal wealth.
Many people falsely believe that opening new checking accounts will severely hurt their credit score. This is simply a myth; bank accounts do not report to credit bureaus like loans or credit cards do.
Opening a standard checking or savings account generally only requires a soft inquiry, which has absolutely no impact on your credit. You can open three new accounts today and your score will remain perfectly intact.
Another major fear is the idea of getting hit with massive monthly maintenance fees. People remember the old days when traditional brick-and-mortar branches charged you just for keeping your money with them.
However, modern digital banks and credit unions offer incredible fee-free accounts that require no minimum balance. You just have to be slightly selective about where you choose to park your cash.
Handling the Unexpected Surprises
Even with the best planning, life will always throw you curveballs that challenge your budget. You might wonder how a rigid structure of separate accounts handles unexpected expenses that pop up out of nowhere.
Let us imagine your car needs new brakes, which will cost you a few hundred dollars. In a single-account system, paying this bill might accidentally drain the money you needed for your mortgage.
But with the multi-account strategy, your bill money is sitting safely behind a protective wall. You simply dip into your separate emergency vault, pay the mechanic, and your core living expenses remain completely untouched.
This separation prevents one single financial crisis from creating a domino effect that ruins your entire life. It acts like compartments on a submarine; if one section floods, the rest of the ship stays safely afloat.
Joint Finances: How Couples Benefit From Separation
Managing money as a single person is hard enough, but bringing a partner into the mix complicates things entirely. Money arguments are one of the leading causes of stress and division in relationships today.
When couples try to dump all their separate incomes into one giant joint account, resentment often builds quickly. One partner might feel frustrated that the other is spending too much on personal hobbies.
The multi-account strategy is an absolute lifesaver for couples trying to navigate shared financial responsibilities. You can create a system that honors your joint goals while still maintaining your personal independence.
The "Yours, Mine, and Ours" Approach
The most successful couples often use a hybrid system to manage their household cash flow smoothly. They open a joint "bills" account where both partners contribute an agreed-upon percentage of their income.
This shared hub pays for the mortgage, the groceries, the utilities, and any shared vacations. But the magic happens with what they do with the remainder of their separate paychecks.
Each partner keeps their own completely separate, private spending account for their own personal wants. If one person wants to buy expensive golf clubs, they use their own private money without asking for permission.
This eliminates the need to constantly check in with each other over small, daily purchases. You get the benefit of working together as a team without losing your individual financial freedom.
Overcoming the Initial Setup Friction
I completely understand that sitting down to open new bank accounts does not sound like a fun weekend activity. Our brains naturally prefer to stick with what is familiar, even if that familiar thing is causing us massive stress.
But you have to weigh the temporary discomfort of setting this up against the long-term pain of financial chaos. Spending two hours organizing your digital life will literally save you hundreds of hours of worry over the next decade.
You do not have to do everything perfectly all at once to start seeing incredible benefits. Even taking one small step will dramatically improve your relationship with your finances.
Start by simply opening one brand-new account just for your fixed monthly bills. Move your rent and utility money over there, and watch how much lighter your chest feels when you check your daily spending app.
Once you experience that initial relief, you will naturally want to continue building out the rest of your system. You are taking control back from the chaos and giving yourself the gift of clarity.Next-Level Strategies for Managing Your Cash Flow Like a Pro
Once you set up your basic hubs and spokes, you might feel a sudden rush of relief. But simply opening the accounts is only the beginning of your journey toward true financial peace.
To make this system work perfectly on autopilot, you need to apply a few clever psychological tricks. These small adjustments will turn your standard banking setup into a highly efficient wealth-building machine.
One of the most powerful habits you can build right now is renaming your accounts inside your banking app. Most digital banks allow you to change the generic account titles to something deeply personal and motivating.
Instead of seeing "Checking Account 0045," you should see a title like "Our Dream Vacation Fund" or "Untouchable Rent Money." This creates a strong emotional connection every time you log in to check your balances.
According to behavioral research from the National Endowment for Financial Education, people are significantly less likely to steal money from themselves when the cash is attached to a highly emotional goal. Naming your accounts forces you to recognize exactly what you are giving up if you overspend.
Mastering the Monthly "Cash Sweep" Technique
If you want to accelerate your savings without feeling pinched, you need to start using the cash sweep method. This is a brilliant little trick that helps you squeeze every last drop of value out of your paycheck.
On the night before your next payday, take a very close look at your guilt-free spending account. If you have any money left over, even if it is just ten dollars, sweep it immediately into your emergency vault.
You should treat this leftover cash as a fun little bonus for being disciplined throughout the month. Over time, these tiny, random transfers add up to a massive safety net.
This habit helps immensely when you are building a cash buffer to protect yourself from unexpected disasters. You essentially trick yourself into saving more money by just cleaning up your digital balance.
Navigating Irregular Incomes and Freelance Money
The multi-account strategy is relatively easy when you receive a steady, predictable salary every two weeks. But things get a little messy if you work on commission, run a small business, or freelance.
When your income jumps up and down every month, keeping your bills paid can feel incredibly stressful. The secret here is to add one extra banking hub to your system, known as the "Holding Tank."
Whenever you get paid by a client, all of that money goes straight into this specific holding account. You never spend directly from this tank, and you never use its debit card for daily shopping.
On the first day of the month, you transfer a fixed, standard "salary" from the holding tank into your regular bills and spending accounts. This smooths out your cash flow, giving you a perfectly normal paycheck even when your business income is totally unpredictable.
Dealing with Sudden Windfalls and Bonuses
Eventually, you will experience a month where extra, unexpected money lands right in your lap. This could be a tax refund, a generous holiday bonus from your boss, or an inheritance.
Most people instantly dump these windfalls into their main checking account and slowly waste the cash on random dinners and clothes. They completely waste a golden opportunity to improve their financial future.
To handle this smartly, you need a pre-written rule for exactly what happens when surprise money arrives. For example, you might decide that half goes straight into your savings vault, and the other half goes into your fun money account.
This removes the temptation to inflate your lifestyle permanently just because you had one good month. By pushing the extra money into designated lanes, you ensure you enjoy the bonus while still making responsible choices.
The Hidden Dangers That Can Break Your New Banking System
I have watched so many friends get incredibly excited about organizing their money, only to completely abandon the system a month later. They usually fail because they stumble into a few common, completely avoidable traps.
When you start rearranging your entire financial life, it is very easy to accidentally make things worse. If you are not careful, you can end up with bounced checks, frustrating penalty fees, and even more anxiety than you started with.
Let us walk through the most dangerous pitfalls you will face during this transition. Recognizing these traps ahead of time will save you from massive headaches and financial heartbreak down the road.
The Temptation of "Account Hoarding"
When people first realize how well this system works, they tend to go totally overboard. They decide they need a separate bank account for groceries, another for gas, another for pet supplies, and one for haircuts.
Before they know it, they are trying to actively manage twelve different digital accounts at the same time. This immediately turns a simple, elegant budgeting strategy into a horrifying administrative nightmare.
You spend your entire weekend manually moving tiny amounts of money around just to buy a bag of dog food. You will eventually get tired of doing this, give up entirely, and go back to your old, messy habits.
To stay sane, stick to the absolute basics: one hub for income, one for fixed bills, one for fun, and one for savings. You only need enough separation to keep your main priorities safe, not a different account for every single purchase you make.
Mixing Up Your Plastic Cards
This sounds like a silly problem, but it is actually the number one reason people accidentally ruin their budgets. When you have three different accounts at the same digital bank, they usually send you three identical debit cards.
If you are standing in line at the grocery store and accidentally swipe your fixed bills card instead of your fun money card, disaster strikes. You just accidentally spent the money meant for your upcoming car payment.
To avoid this stressful scenario, you have to create a foolproof physical system for your wallet. I highly recommend taking a bright permanent marker and writing "FUN" or "BILLS" heavily on the back of each card.
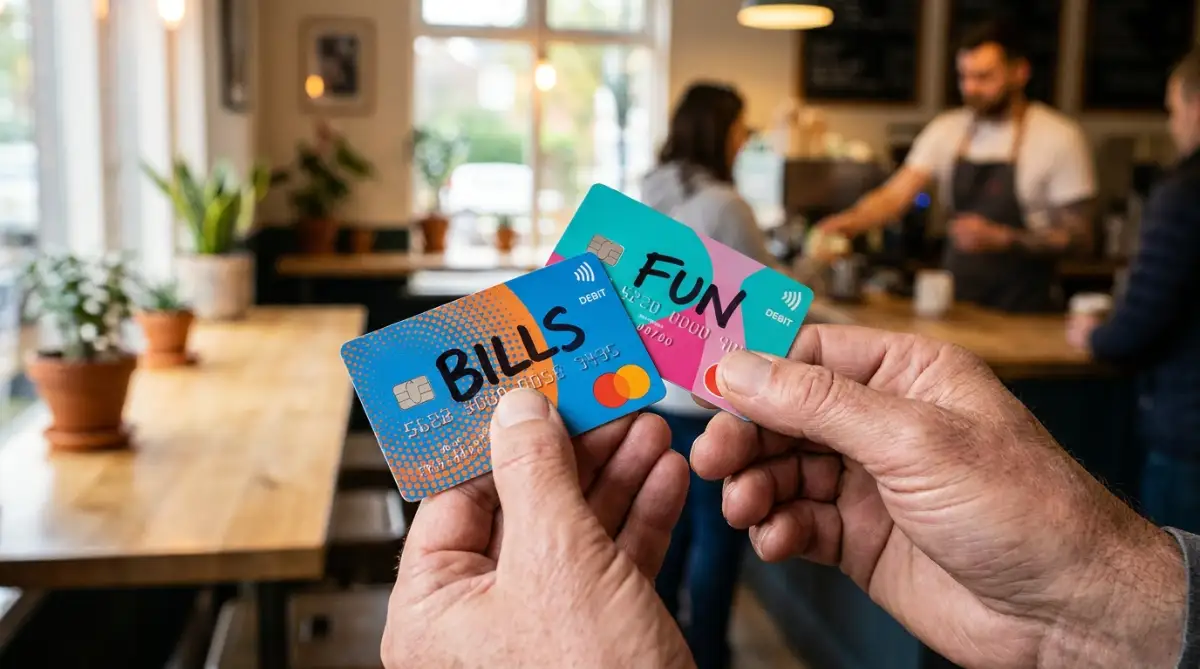
Even better, load your daily spending card into your phone's digital wallet and leave the rest of the plastic cards safely at home in a drawer. If the bills card is not in your pocket, you literally cannot spend your rent money on a sudden impulse purchase.
My Personal "Card Lock" Trick: If you still find yourself cheating the system and using the wrong digital card on your phone, go into your mobile banking app and hit the "Lock Card" button on your Bills account. Most modern banks let you toggle this feature on and off instantly. Keep that specific card locked 29 days a month, and only unlock it on the exact day you need to pay a major bill. It physically stops you from making a mistake!
Ignoring the Silent Threat of Minimum Balance Fees
As we discussed earlier, the internet is full of amazing digital banks that offer completely free services. But some traditional, older banks still secretly charge you money just for keeping your accounts open.
They might offer you a free account, but hide a sneaky rule in the fine print. According to data from the Consumer Financial Protection Bureau, confusing maintenance fees are one of the biggest complaints everyday consumers have about their banks.
If your balance drops below five hundred dollars, they might suddenly hit you with a fifteen-dollar penalty fee. If you have your cash split across multiple accounts, keeping high balances everywhere is nearly impossible.
You must read the terms and conditions very carefully before you open anything new. If a bank demands a minimum balance to waive their monthly fees, run far away and find a truly free alternative.
Forgetting to Update Your Automatic Payments
When you finally set up your brand new fixed bills account, you have to do a little bit of manual homework. You have to actively go into your Netflix, utility, and insurance portals to update your payment information.
Many people get lazy and forget to switch these over from their old, messy checking account. When the bill comes due, the old account has no money in it, and the payment completely fails.
This can lead to nasty late fees, canceled services, and a sudden drop in your personal credit score. It can also cause severe issues if you are currently relying on a mortgage amortization schedule and you miss a scheduled house payment.
Take one quiet Sunday afternoon, sit down with a cup of coffee, and change every single billing profile to your new dedicated account. Doing this right the first time guarantees your system will run flawlessly moving forward.
Your Action Plan for Total Financial Clarity
Organizing your wealth does not require extreme intelligence, confusing spreadsheets, or punishing yourself for buying things you enjoy. It simply requires you to build a banking environment that gently guides you toward the right decisions.
By separating your non-negotiable bills from your fun money, you automatically eliminate the emotional stress of daily spending. You stop guessing if you have enough cash, and you start knowing exactly where every dollar belongs.
This structure gives you the freedom to dream bigger than just surviving from one payday to the next. Whether you are saving up for a fun vacation or secretly planning a property purchase, this system ensures your money is always moving in the right direction.
You will finally break the cycle of accidental overdrafts and stop feeling guilty about treating yourself to a nice dinner. Your money becomes a helpful tool that supports your lifestyle, rather than a confusing puzzle that keeps you awake at night.
If you ever find yourself in a tight spot where you need external funding, having clean, organized accounts will also make getting a bank loan significantly easier. Lenders love to see someone who cleanly separates their cash and pays their bills automatically on time.
Proper organization also acts as a powerful protection for you and your company if you ever decide to run a side business. Keeping your personal and business cash completely isolated is the golden rule of entrepreneurship.
My best advice for you today is to start incredibly small and not let the fear of change hold you back. Just opening one single account for your fixed bills this week will completely transform the way you feel about your paycheck. I remember sitting at my kitchen table, terrified of setting all this up, but the moment I separated my rent money from my food money, I finally felt like I could breathe again. You absolutely have the power to take control of your wallet right now, and I promise you will never want to go back to your old ways!
Common Questions About Organizing Multiple Bank Accounts
Does opening multiple checking accounts hurt my credit score?
No, opening standard bank accounts generally has absolutely zero impact on your personal credit score. Banks typically only perform a very soft background check to verify your identity, which never shows up on your standard credit report. You can safely open several checking or savings accounts without worrying about damaging your credit history.
How many bank accounts should a normal person actually have?
Most financial experts agree that having three to four specific accounts is the perfect sweet spot for everyday people. You generally need one for incoming money, one for your fixed monthly bills, one for daily fun spending, and one high-yield savings account for emergencies. Having any more than five can start to feel completely overwhelming and messy.
Should I keep all my different accounts at the same exact bank?
It is completely fine to keep your checking, bills, and fun money at the same institution for quick, instant transfers. However, you should strongly consider putting your emergency savings at a totally different bank so you are not tempted to touch it. This physical separation forces you to pause and think before you try to spend your safety net.
What happens if I accidentally use the wrong debit card for a purchase?
If you accidentally use your bills card for a fun purchase, do not panic at all. Simply log into your mobile banking app as soon as possible and transfer the exact amount from your fun account back into your bills account. To prevent this from happening again, consider wrapping a piece of colored tape around the card you should rarely use.
Are there any tax implications for having money spread across different banks?
Having your cash spread across multiple different institutions does not complicate your standard tax situation at all. The only thing you need to watch for is the interest you earn on your various savings accounts throughout the year. If your separated savings accounts earn significant interest, those specific banks will send you a basic tax form to report that small extra income.
Disclaimer: The information provided in this blog post is for educational and informational purposes only and does not constitute professional financial advice. Everyone's financial situation is entirely unique, so please consult with a certified financial planner or advisor before making any major changes to your personal banking structure.


