The Shocking Truth About Your Final Home Bill
You finally get the keys to your new house. You should be popping champagne, right? Instead, you are staring at your closing statement, wondering where an extra $3,000 in mystery fees came from. I have been in that exact spot, feeling totally blindsided by a stack of paperwork. Let me show you how lenders slip these hidden charges past you—and exactly how you can cross them out before you sign anything.
Panic washed over me instantly. I felt completely trapped because pulling out meant losing the house I already loved. It was a brutal, heartbreaking wake-up call about how sneaky the home-buying process can actually be.
You work incredibly hard to save for a home. You track your expenses, build your credit score, and finally get that exciting approval letter.
But behind the scenes, a different game is being played with your money. Regular, hardworking families are dipping into their emergency funds just to cover expenses they did not expect.
How Sneaky Lender Charges Empty Your Pockets
What You Will Learn in This Guide:
- Spot the Junk: How to identify completely fake charges like "email fees" and get them wiped out.
- The End-of-Month Trick: Why scheduling your closing on the 28th saves you a ton of upfront cash.
- Title Shopping: My exact method for picking your own title company instead of using the bank's expensive partner.
- Protect Your Credit: Why buying a new couch on credit before closing day can freeze your entire loan
We are going to break down exactly how your money gets quietly taken away during the final stages of buying a house. More importantly, I am going to show you how to fight back.
You do not have to accept every single number printed on that paper. You have the power to ask questions, demand changes, and keep your own hard-earned cash.
The Phantom Application and Processing Trap
Let us start with one of the most common tricks in the book. When you first apply for a loan, some lenders charge an upfront "application fee."
They tell you this covers the cost of checking your credit and setting up your file. But here is the reality: pulling a credit report costs them barely anything.
Of course not. Many lenders try to stack a "processing fee" on top of this as well. They claim it pays for the staff who organize your paperwork.
But guess what? Organizing paperwork is their actual job. You should never be punished financially for the basic administrative work a company needs to do to function. Always ask them to waive these upfront fees.
Quick Cheat Sheet: Which Fees Are Fake?
I always keep a mental checklist to separate real costs from lender cash grabs. Here is a quick table to help you spot the difference instantly:
Origination Illusions: Paying for Nothing
Next on the list is the loan origination fee. This is often the biggest shocker for new buyers.
Lenders usually charge about one percent of your total loan amount for this single fee. If you are borrowing three hundred thousand dollars, that is a sudden three thousand dollar charge added to your bill.
They say this is their compensation for putting the loan together. But wait a minute, are they not already making massive profits from the interest you will pay over the next thirty years?
Yes, they absolutely are. Origination fees are highly negotiable.
Many buyers simply nod their heads and accept it because the number looks official. But if you push back and ask them to lower or remove it, you will be surprised at how quickly they can adjust the numbers to keep you as a customer.

Are you ready to see exactly how these fees are structured and how to spot them on your loan estimate? Watch this quick breakdown before moving to the next step.
Title Services and The "Required Vendor" Illusion
When you buy a house, you need title insurance to prove the property legally belongs to you. It protects both you and the bank from future legal troubles.
Your lender will usually hand you a list of "required" or "recommended" companies to handle this title search and insurance process. What they do not tell you is that these companies are often their business partners.
They charge premium rates because they know you are too tired to shop around. You actually have the legal right to choose your own title company in most cases.
By spending just one hour calling local independent title companies, you can easily save hundreds of dollars. The bank’s recommended list is meant for their convenience, not your wallet.
Always remember that shopping around is your best defense against inflated prices.
Pro Tip from My Own Experience: I once let a lender choose my title company without questioning it, and I ended up paying almost double the local average. The very next time I bought property, I made three quick phone calls to independent title agents in my town and saved roughly six hundred dollars on the exact same service. Never assume the bank’s preferred partner is giving you a fair deal.
The Sneaky "Rate Lock" Extension Penalty
Interest rates change every single day. When you find a rate you like, your lender will lock it in for a specific time, usually thirty to sixty days.
This guarantees your monthly payment will not suddenly jump up before you get the keys. But what happens if the closing is delayed?
Maybe the seller needs more time to move out, or the bank is taking too long to review your tax returns. If your rate lock expires because of these delays, lenders will suddenly charge you a "rate lock extension fee."
This can cost you a massive chunk of money. The most unfair part is that the delay is almost never your fault!
If the bank is the one moving slowly, you should firmly demand that they cover the extension cost. Do not let them penalize you for their own slow paperwork.
The Junk Fee Graveyard: Where Small Charges Add Up
Sometimes, lenders do not hit you with one massive fee. Instead, they bleed your bank account dry with a dozen tiny charges.
Industry insiders actually call these "junk fees." You will see line items like "Document Preparation Fee," "Wire Transfer Fee," "Courier Fee," or even "Email Fee."
Yes, some companies actually try to charge you for sending emails. When you look at them individually, fifty dollars here or seventy-five dollars there does not seem too scary.
But when you add up ten different junk fees, you are suddenly looking at a thousand dollars missing from your savings. These fees are entirely made up.
They are designed to pad the lender’s profit margin right at the finish line. When you spot these on your loan estimate, grab a red pen and circle every single one of them.
Call your loan officer and ask them to explain exactly what a "document preparation fee" is. Usually, when you call them out on these nonsense charges, they will quietly remove them just to avoid an argument.
Myth vs. Reality: The Truth About Escrow Buffers
Let us look at a very common misunderstanding that drains your cash.
The Myth: The bank needs you to put an extra six months of property taxes and home insurance into an escrow account just to keep your home safe from the government.
The Reality: While escrow accounts are standard, lenders often demand way more money upfront than they actually need. They call it a "buffer" or a "cushion."
By forcing you to overfund your escrow account, they get to hold onto your cash. You are basically giving them a free loan.
Federal law actually limits how much extra padding a lender can force you to put into an escrow account. Usually, it is only a two-month cushion.
If you see them asking for five or six months of taxes upfront, you need to push back immediately. Ask them to recalculate the escrow requirements based on the legal minimum.
Keeping that cash in your own pocket means you have money to buy furniture, paint walls, or handle actual emergencies.
How to Read the Closing Disclosure Like a Detective
Three days before you sign the final papers, the law requires your lender to give you a document called the Closing Disclosure.
Most people just glance at the final big number at the bottom and hope for the best. That is exactly what the bank wants you to do.
You need to treat this document like a detective treats a crime scene. Put it side-by-side with the original Loan Estimate they gave you weeks ago.
Look carefully at every single row. Did the origination fee suddenly increase by a few hundred dollars?
Did a mysterious "notary fee" magically appear out of nowhere? By law, certain fees are not allowed to increase at all, and others can only increase by ten percent.
If a fee jumps up higher than the legal limit, the lender actually has to refund you the difference. But they will not do it voluntarily.
You have to point it out to them. The three-day rule exists specifically so you have time to catch these mistakes before you sign your life away.
Do not let anyone rush you through this review process.
The Appraisal Markup Game
When you buy a house, a professional appraiser has to visit the property to confirm its real value. You always have to pay for this service.
An average appraisal costs somewhere around four hundred to five hundred dollars. However, some lenders use their own internal appraisal management companies.
Instead of passing the exact cost on to you, they mark it up. They might pay the appraiser four hundred dollars but charge you six hundred dollars on your final bill.
They pocket the difference as pure profit. You have the right to ask for the actual invoice from the appraisal company.
If the invoice says four hundred dollars, but your closing document says six hundred, you have caught them red-handed. Demand that they adjust your bill to match the actual cost of the service.
Every single dollar you save here is a dollar that stays in your checking account.
My Personal 60-Second Email Script:
Whenever I catch a lender marking up a third-party fee like an appraisal, I send a very simple message: "Hi [Name], I noticed the appraisal fee is listed at $600. Can you please send over the direct invoice from the appraisal company so I can review it?" In my experience, if they marked it up, the extra charge magically disappears from the updated paperwork the very next morning.
Protecting Your Hard-Earned Down Payment
Buying a house is an emotional rollercoaster. By the time you reach the final week, you are probably exhausted.
You just want the keys so you can start moving your boxes. Lenders know exactly how tired you are.
They count on your fatigue. They assume you will just sign anything to make the process end.
But this is the exact moment you need to stay sharp. The money they are trying to take is money you traded your precious time and energy to save.
Do not give it away just because a printed piece of paper looks official. Question everything, negotiate boldly, and protect your family's financial future.
Now that you understand the tricks they play, you are already one step ahead of the average homebuyer. You are armed with the right knowledge to keep your bank account safe from these silent drainers.
Next-Level Tactics to Keep Your Closing Costs Near Zero
Most homebuyers assume that once the bank prints a number on a piece of paper, that number is set in stone. This is exactly what the banking industry wants you to believe.
However, behind closed doors, almost every single charge on your loan estimate is highly negotiable. You just need to know exactly which buttons to push before you sign anything.
If you are serious about keeping your savings intact, you must start treating your mortgage application like a competitive bidding war. Your biggest weapon is your ability to walk away and take your business to another lender.
The Magic of Comparing Loan Estimates
Imagine you are buying a brand new television. You would never just walk into one single electronics store, pick the first TV you see, and hand over your credit card without checking prices online.
Buying a house is the largest financial transaction of your life, yet most people only talk to one single bank. This loyalty costs average families thousands of dollars in inflated fees.
To protect yourself, you need to apply with at least three different lenders on the exact same day. When you do this, you will receive three separate official loan estimates to lay side-by-side on your dining table.
This gives you a clear visual map of who is trying to overcharge you. If one bank charges a massive processing fee but another bank does not, you can instantly spot the difference.
According to guidelines from the Consumer Financial Protection Bureau (CFPB) on comparing loan estimates, shopping around can save you a significant amount of money over the life of your loan. You can take the cheapest estimate, show it to your preferred bank, and simply ask them to match it.
Most of the time, they will drop their junk fees instantly just to keep you from walking away to a competitor. It is a simple conversation that takes five minutes but can save you a small fortune.
Mastering the End-of-Month Scheduling Trick
Here is a brilliant insider secret that very few real estate agents will tell you about. The exact day of the month you choose to sign your final closing papers heavily impacts how much cash you need to bring to the table.
When you close on a house, your lender makes you pay "prepaid interest" for the remaining days of that current month.
Let us look at a real-life scenario to see how this works. If you schedule your closing date for the fourth day of the month, you have to pay interest for all the remaining days left in that month.
That means you are paying nearly thirty days of pure interest out of your own pocket upfront. On a standard loan, that could easily add over a thousand dollars to your final closing bill.
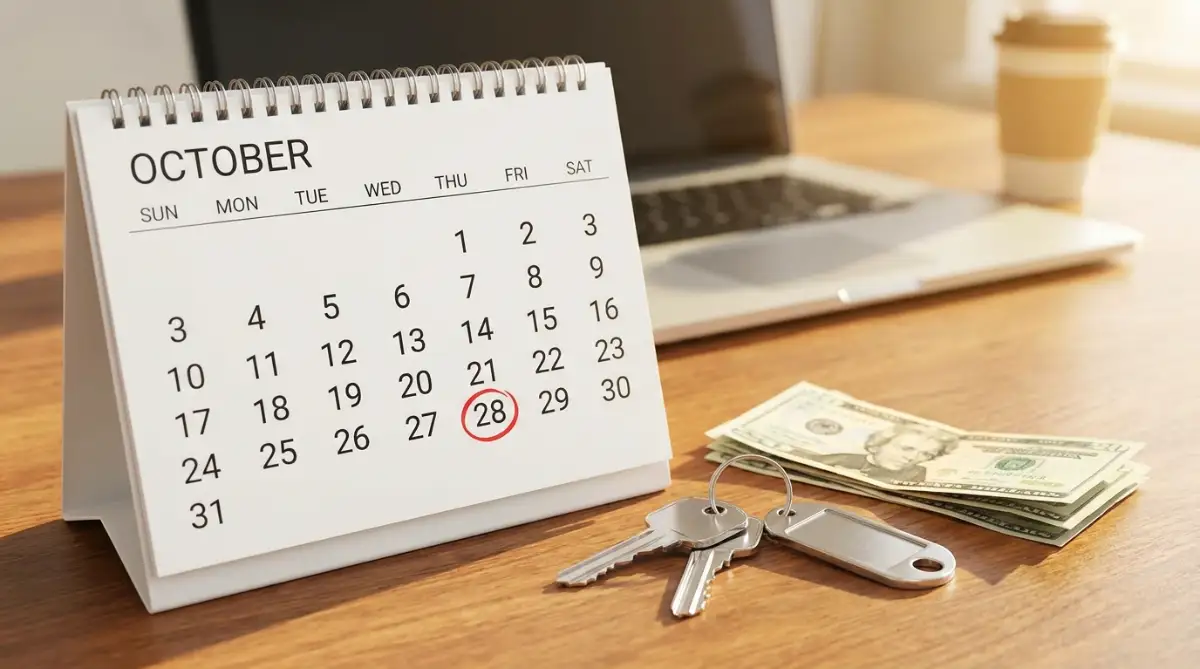
Now, imagine you schedule your closing date for the twenty-eighth day of the month instead. You only have to pay upfront interest for those two or three remaining days.
This simple calendar adjustment keeps a massive chunk of money resting safely in your bank account. It is one of the easiest ways to build a strong financial foundation while mastering the home buying process without taking on extra stress.
Understanding Lender Credits vs. Out-of-Pocket Cash
Sometimes, you might find yourself completely short on cash as closing day approaches. Maybe your moving expenses were higher than expected, or your car suddenly needed repairs.
If you are struggling to cover the final closing costs, you can actually ask your bank for something called "lender credits."
Here is how this financial tool works in plain English. The bank agrees to cover a large portion of your upfront closing fees for you.
In exchange, you agree to take a slightly higher monthly interest rate on your loan.
For example, instead of paying five thousand dollars out of pocket today, the bank pays it. Your monthly mortgage bill might just go up by thirty or forty dollars a month.
If you plan to live in the house for just a few years before moving again, taking lender credits is an incredibly smart move. It allows you to keep your immediate cash while creating a solid savings safety net for emergency home repairs.
The "Do Not Ask, Do Not Get" Rule
At the end of the day, you have to be your own biggest advocate. Lenders are running a business, and their primary goal is to maximize their profit on your loan.
They are never going to voluntarily call you up and offer to remove a document preparation fee. You have to point directly at the charge and say, "I am not paying this."
I have seen people successfully negotiate everything from courier fees to administrative charges just by asking firmly. Treat this process like a respectful business negotiation.
If you act confident and show them you understand how the numbers work, they will treat you with much more respect.

Dangerous Blunders That Cost Homebuyers Thousands
Even the smartest buyers can fall into carefully laid traps if they let their emotions take over during the final weeks of buying a house. The excitement of packing boxes and picking out paint colors often distracts people from the boring financial paperwork.
This is exactly when costly mistakes happen. Let us look at the most common ways people accidentally throw their money away right before getting their keys.
The Loyalty Trap: Feeling Bad for Your Loan Officer
Many buyers build a very friendly relationship with their loan officer during the application process. You spend hours on the phone with them, sharing your financial history and talking about your future plans.
Because of this friendly bond, people feel guilty pushing back on fees or shopping around with other banks.
Please remember that your loan officer is a salesperson, not your family member. Their warm personality is part of their job description.
You should never feel bad about protecting your own family's financial future. If you discover they are charging you a ridiculous application fee, you must speak up.
If you are trying to find ways of securing a standard bank loan without pledging assets, you already know that financial loyalty must be earned, not given blindly. Always put your own bank account above someone else's sales commission.
The Silent Credit Killer Before Closing
This is perhaps the most heartbreaking mistake a new buyer can make, and it happens every single day. A week before closing, a family decides to go to a furniture store to buy a new couch and refrigerator for their new home.
The store offers them a special financing deal, so they open a new credit card right there at the checkout register.
What they do not realize is that lenders pull your credit report one final time just days before your closing date. Opening a new credit account completely changes your debt-to-income ratio.
The bank will immediately freeze your loan process and force you into a stressful re-underwriting phase.
Not only can this delay your closing, but the bank might also hit you with new penalty fees or even increase your interest rate. The Federal Trade Commission (FTC) strongly advises consumers against making any large purchases or applying for new credit while a mortgage is pending.
Your best defense is to freeze all your spending completely until the keys are physically in your hands. Sleep on a mattress on the floor for a week if you have to.
Ignoring the Closing Disclosure Until the Last Minute
By law, you must receive your Closing Disclosure three full business days before you sign the final papers. This rule exists specifically to protect you from last-minute surprise charges.
Yet, surprisingly, a huge number of buyers simply open the email, glance at the final total, and go back to packing boxes.
They assume the bank did the math correctly. This is a massive, expensive error in judgment.
You need to sit down in a quiet room, grab a cup of coffee, and compare this new document line-by-line with your original estimate.
Did the appraisal fee suddenly jump up by two hundred dollars? Are there strange new line items under the title service section?
If you wait until you are sitting at the lawyer's table to read these numbers, it is too late to argue. You will be so pressured to finish the deal that you will just sign away your money.
Taking the time to review this document is a key step in protecting your personal finances and business assets legally from predatory lending practices.
Accepting Inflated Title Insurance Costs
As we discussed earlier, title insurance is completely mandatory, but the company you buy it from is not. Many buyers make the huge mistake of just accepting the title company their real estate agent or lender writes down on the form.
They assume the price is regulated or standardized across the industry.
The truth is, title fees vary wildly from one company to another. Some companies charge massive hidden search fees or courier charges on top of the base insurance premium.
If you do not pick up the phone and call three different local title companies to compare prices, you are basically handing out free money. It takes less than thirty minutes of research to save what could easily equal a week's worth of your salary.
Your Blueprint for a Stress-Free Closing Day
You now have a powerful understanding of how the mortgage industry tries to squeeze extra money out of your pockets. You know exactly what junk fees look like, how to spot them on your documents, and how to demand their removal.
More importantly, you have the confidence to treat this process like a business deal rather than a favor from the bank.
Let us turn everything we have discussed into a simple, highly effective action plan you can start using tomorrow.
Tomorrow's Action Plan for Homebuyers:
- Audit Your Initial Estimate: The moment you receive your very first loan estimate, grab a highlighter. Mark every single charge under the "Origination Charges" and "Services You Cannot Shop For" sections. These are your main negotiation targets.
- Request Fee Waivers Early: Do not wait until the end of the process to complain about costs. Call your loan officer within twenty-four hours of receiving the estimate and ask them to waive their processing and application charges.
- Map Out Your Timeline: Look at a calendar and actively request a closing date near the very end of the month. This will aggressively cut down your upfront prepaid interest costs. Understanding these timelines is just as helpful as understanding how to read your mortgage repayment timeline for long-term success.
- Set a Spending Freeze: Put a sticky note on your wallet reminding you not to apply for any credit cards, buy any cars, or make large furniture purchases until after closing day.
- Demand the Actual Invoices: If your bank charges you for an appraisal or a credit report, calmly ask them to provide the third-party receipt. Make sure they are not marking up the price for their own profit.
I remember how terrifying it felt to sign those closing papers, constantly worrying if I was being scammed out of my savings. I want you to feel nothing but pure joy and excitement when you finally turn the key in the front door of your new home. By actively questioning these fees and standing your ground, you are not just saving money; you are protecting the beautiful future you have worked so incredibly hard to build.
Real Questions Buyers Ask About Surprise Closing Charges
Can I legally refuse to pay a mortgage junk fee?
Yes, you absolutely can refuse to pay unnecessary junk fees, but you have to do it before you sign the final papers. If you spot a ridiculous charge like an "email fee" or "document prep fee," you can tell your lender to remove it or you will take your loan to another bank. Most lenders will quickly waive these small fees to save the overall deal.
What happens if my Closing Disclosure numbers are completely wrong?
If the numbers on your Closing Disclosure are much higher than your original Loan Estimate, you must contact your lender immediately. By federal law, certain fees are heavily restricted and cannot increase at the last minute. If the bank made an error, they are legally required to fix the document and refund you the difference.
Should I drain my emergency fund to cover unexpected closing costs?
You should never drain your entire emergency fund just to cover surprise bank fees. If you are extremely short on cash, talk to your lender about taking "lender credits" to cover the closing costs in exchange for a slightly higher interest rate. It is much safer to have cash in the bank for home emergencies than to give all your money to the lender upfront.
Does shopping for different lenders hurt my credit score?
You can shop for multiple mortgage lenders without ruining your credit score. As long as you submit all your mortgage applications within a short time frame, usually around fourteen to forty-five days, the credit bureaus count it as one single inquiry. This allows you to compare fees safely without damaging your financial profile.
Is it normal for a lender to ask for six months of taxes upfront?
While lenders do require you to fund an escrow account for taxes and insurance, asking for six months upfront is often excessive. They usually only need enough to cover the upcoming bills plus a legal two-month cushion. If they ask for massive upfront tax payments, ask them to show you the exact math based on federal escrow limits.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial, legal, or real estate advice. Mortgage rules, interest rates, and lending laws change frequently and vary by location. Always consult with a licensed financial advisor, real estate attorney, or certified mortgage professional before making major financial decisions or signing legal contracts.